What’s in the box: Is your business rates relief scheme still effective?
Over the summer the Court of Appeal gave judgment on an appeal brought by the City of London, relating to a rates mitigation scheme. The decision will be of keen interest to any landlords trying to manage their liability for non-domestic rates, or business rates. The court found that a common existing scheme is not effective. The ruling aligns the court with the much stricter approach we are seeing tax authorities are taking. The case itself was The Mayor and Commonalty and Citizens of the City of London v 48th Street Holdings Ltd & Another [2026] EWCA Civ 970 (KB).
It goes without saying that any landlords who use these or similar schemes should speak to their legal advisors.
The scheme
The scheme in question is a common one:
- A landlord has empty premises, and has used up the period of relief from paying business rates.
- A third party rates mitigation business (the “tenant”) takes a lease of empty premises from the landlord.
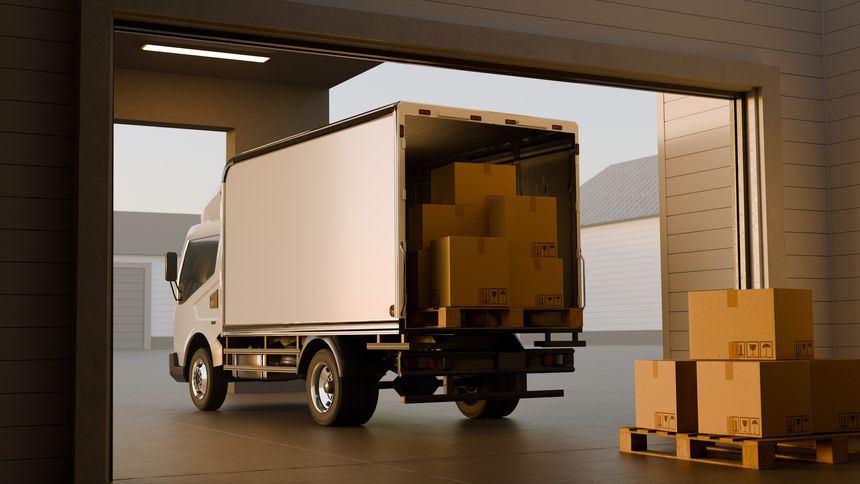
- The tenant moves some materials (in this case boxes) into the premises and occupies (via the boxes) for long enough that the landlord will be able to claim empty rates relief.
- The tenant accepts liability for business rates during its period of occupation. As between the landlord and the tenant, the landlord invariably makes a payment to the tenant at least equal to the business rates payment.
- When the tenant later vacates, the landlord is able to claim rates relief, and the tenant takes a success fee.
These schemes have been controversial for many years, with local authorities challenging them with varying degrees of success. However the High Court has previously found a similar scheme to be effective at resetting the landlord’s entitlement to business rates relief.
The ruling
In this case, the Court of Appeal overturned the previous ruling by the High Court that had upheld these types of schemes. It is relevant to this case that it was common ground that the occupation was only for the benefit of rates mitigation; it was relevant that there was nothing in the boxes that the tenant needed to store. The Court said if the only benefit for the tenant was to achieve rating relief, that did not count as occupation and would fall foul of other case law whereby the Court will not uphold a structure that has been created purely to reduce a party’s tax liability. That would run contrary to the intention of the legislation.
What now?
Landlords will want to assess any existing arrangements in light of the judgment.
As things stand, use of schemes such as the one considered by the Court will not allow a landlord to benefit from repeat empty rates relief. Given the ruling could constitute an existential threat to the rates mitigation business involved, a further appeal to the Supreme Court may be in the works. Watch this space.
Landlords who are looking to mitigate rates liability will still have other avenues open to them, such as lettings to pop-ups or other occupiers. Equally, given the emphasis placed on ‘what was in the boxes’, it may be that the case might have been decided differently if the boxes had contained something that needed to be stored – for example, archive material.
Subcribe to news and views"something done for no purpose other than the avoidance of liability for rates will be ineffective in achieving that purpose" - Lady Justice Falk