Five things the Gen+1 Elevate conference made clear about the data centre market

Commercial real estate

I attended the Gen+1 Elevate conference last week as part of the Forsters data centre team.

Demand for data centres is accelerating. That is no longer up for debate.

The more interesting question, and the clear theme from the panels, is whether projects can actually be delivered.

Across the panels, five themes stood out.

1. The real investment story is about execution, not yield

The numbers still work. Yields of 8-9%, and 5-7 year investment horizons continue to attract capital.

Investor focus, however, has clearly shifted.

The key question is no longer “should we invest?” but “can this scheme actually be built?”

That is driving a much sharper focus on:

  • planning risk;
  • power availability and timing; and
  • delivery capability and access to labour.

The rise of joint ventures reflects this. Investors are increasingly looking to partner with operators, energy providers and developers to access expertise they do not have in-house.

Collaboration though brings complexity. Alignment of interests, exclusivity and the risk of partners becoming future competitors are now live issues that need to be addressed early.

2. The definition of a “good site” is changing rapidly

Five years ago, a data centre site had a relatively clear profile. That is no longer the case.

Constraints around power, land and scale are forcing developers to rethink location and design. Sites that would previously have fallen outside the investable universe are now being revisited.

Flexibility is becoming the defining characteristic.

There was also a degree of realism in the room. Certain trends, particularly around modular solutions and aspects of the AI ecosystem, were openly described as over-hyped. The expectation is that the market will consolidate, with a limited number of long-term winners.

3. Power is no longer a constraint. It is the constraint

Every conversation ultimately came back to power.

The gap between demand and available capacity is now well understood. What is less well understood is the complexity behind it.

As we are seeing on our projects, “having power” is not a binary issue. It raises a series of more difficult questions:

  • when will it be available;
  • how reliable is it; and
  • what infrastructure is required to support it.

Operators are responding in different ways. Some are exploring on-site, behind the meter, generation and alternative energy solutions. Others are seeking greater control of their supply chain to reduce reliance on constrained infrastructure.

The conclusion is clear. Power availability, in both timing and structure, is now the single biggest factor in determining whether a project proceeds.

4. The delivery model is under strain

Even where land and power are secured, delivery is far from straightforward.

Supply chains are stretched, with long lead times for key components, including fibre. At the same time, there is a growing disconnect between leasing expectations and construction timelines.

The industry is also facing a significant skills gap. Quite simply, there are not enough people to build what is currently in the pipeline.

In response, operators are:

  • bringing parts of the supply chain in-house;
  • increasing use of prefabrication; and
  • using AI to improve productivity and safety.

These are mitigation strategies rather than solutions. Delivery risk remains a core issue.

5. Planning and perception are becoming commercial issues

Planning is no longer just a legal or regulatory hurdle. It is a commercial one.

There is increasing scrutiny of how data centres are perceived at the development stage, particularly in relation to energy use and pressure on infrastructure.

At the same time, the industry is not always effective at communicating the value data centres generate. The economic impact of large-scale schemes is significant, but often poorly understood outside the sector.

This is creating a need for better engagement, clearer messaging and a more coordinated approach to how the industry presents itself.

What this means for clients

The takeaway is clear. Demand is not the problem. Delivery is.

For investors, developers and operators, that shifts the focus to execution from the outset. In practical terms, that means:

  • Front-loading strategy so that planning risk, power timelines and deliverability are assessed early;
  • Structuring partnerships carefully, with clear alignment on roles, risk and long-term strategy;
  • Taking a holistic view of viability, recognising that land, planning, power and infrastructure need to be considered together;
  • Actively managing delivery risk, particularly in relation to supply chain, skills and program assumptions;
  • Retaining flexibility, both in site strategy and structuring, as requirements continue to evolve.

The projects that succeed will not necessarily be those with the best sites or the strongest demand. They will be the schemes where planning, power, capital and capability are aligned from day one.

That alignment is now where the real value sits.

If any of these themes resonate, get in touch with Forsters’ data centre team. We are already advising on these challenges across a range of projects and bring the depth of experience needed to deliver them successfully.

Demand is not the issue. Delivery is. Five practical takeaways from Gen+1 Elevate on what is really driving the data centre market.
A fundamental shift for physical retail…

Commercial real estate

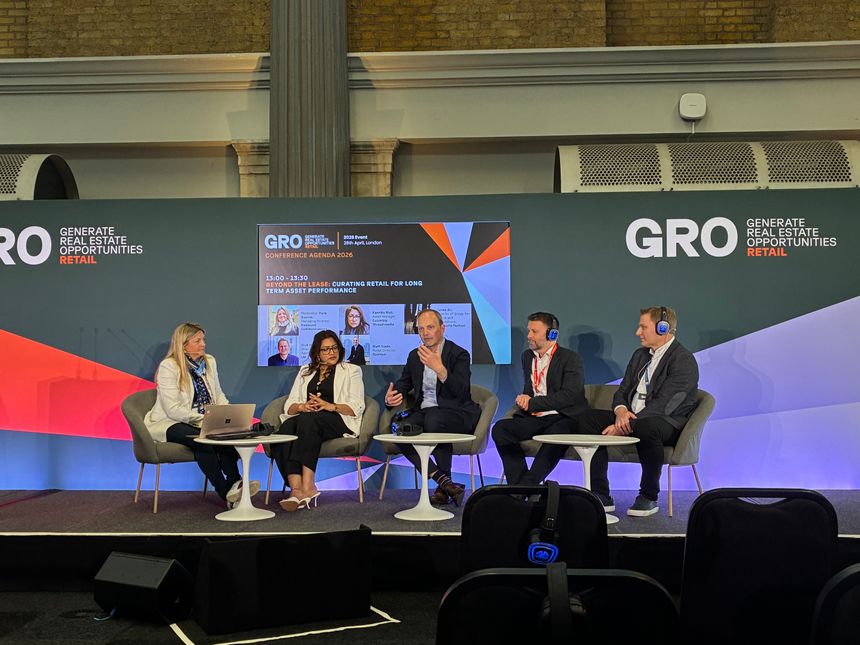
It was great to see so many familiar faces at the GRO spring event last week. 

I also managed to attend a couple of interesting panel sessions and the overwhelming theme was that there has been a fundamental shift in what success looks like for physical retail and shopping centres. 

Physical stores are no longer just a space to sell products. They are a data channel, a place to showcase, a place to create experiences and draw attention and a place to foster brand loyalty. Whilst a material amount of actual purchases may take place online, physical stores are still an important part of the retail business model.

We have seen a rise in pop-up stores, where smaller businesses can test their readiness for physical retail and gather data. A physical space allows these businesses to create a closer connection with their customers, obtain real-time feedback on their products and generate hype.

Combined with the diversification of offerings (think gyms, health centres and leisure), shopping centres are becoming community hubs and driving footfall. There is a more scientific approach to matching services with community needs as well as mixing long-standing, reliable brands with new and exciting concepts.

For many years the turnover rent lease has prevailed. However, I have to wonder if the measure of success of a physical store moves towards promotion rather than sales, we may see a re-imagining of the rack rent lease model to reflect the ever-changing partnership between landlords and occupiers.

When data centres become targets: a legal wake‑up call on resilience, data sovereignty and energy security

Commercial real estate

Recent attacks on data centres during the ongoing conflict involving Iran underline a stark reality. Data centres are no longer just commercial assets. They are strategic infrastructure.

Their targeting reflects how deeply digital infrastructure is embedded in modern economies. Banking systems, healthcare, logistics, government services and AI platforms all rely on uninterrupted access to data. When data centres fail, the consequences are immediate, wide‑ranging and often legally complex.

For businesses, developers and investors, this marks a shift. Operational resilience, data sovereignty and energy security are now legal and strategic considerations, not simply technical ones.

Resilience is becoming a legal obligation

Historically, resilience was addressed through service levels and technical design. That position is changing rapidly.

In the UK, data centres have been designated Critical National Infrastructure, and forthcoming reforms to the cyber and resilience regime will bring large data centres directly within the scope of regulatory oversight. Operators will be expected to demonstrate appropriate and proportionate measures to manage physical, cyber and operational risk, alongside mandatory incident reporting.

From a legal perspective, this raises key questions:

  • How resilience obligations are allocated between landowners, developers, operators and occupiers.
  • Whether existing leases, options, development agreements and collateral warranties adequately address business continuity, outages and force majeure.
  • The extent to which resilience commitments should be reflected in planning conditions, infrastructure agreements and funding documentation.

Standards such as ISO 22301 (Business Continuity) and ISO/IEC 27001 (Information Security) are increasingly relevant as reference points when assessing whether resilience measures are reasonable or market standard. This is particularly so in disputes, regulatory scrutiny or transactional due diligence.

Data sovereignty moves from policy to property

The conflict also sharpens the focus on where data is stored and under whose control.

Data sovereignty is no longer driven solely by data protection law. Geopolitical risk, sanctions exposure and national security considerations are influencing decisions about site selection, ownership structures and operational control of data centres.

For the UK and EU, this is accelerating demand for:

  • In‑country and sovereign data centre capacity.
  • Greater scrutiny of foreign ownership and control.
  • Contractual restrictions on data location, access rights and cross‑border failover arrangements.

From a property and development perspective, this has implications for planning strategy, investment structuring, joint ventures and long‑term asset value, particularly where sites are intended to support public‑sector, regulated or sensitive workloads.

Energy security becomes part of resilience

Recent events in the Middle East underline a further and often under‑appreciated risk. Data centre resilience is inseparable from energy security.

The current conflict involving Iran has driven a sharp increase in global oil prices, compounded by Qatar’s unprecedented decision to halt oil production. That development alone has exposed the fragility of global energy supply chains and the speed at which geopolitical events can translate into economic and operational instability. For infrastructure reliant on continuous, high‑volume power, the implications are immediate.

In this context, energy strategy is no longer just a question of cost or sustainability. Secure, controllable access to power is now a core resilience issue.

While the sustainability case for renewables is well established, the energy security case cannot be undervalued. On‑site and locally generated power, including wind, solar and tidal energy, can reduce dependence on volatile international markets and exposed fuel supply routes when paired with appropriate storage and grid balancing. Small Modular Reactors (SMRs) are also increasingly being examined as a potential long‑term solution for delivering stable, low‑carbon baseload power to energy‑intensive infrastructure such as data centres.

For developers, investors and occupiers, this reframes energy procurement as a legal and strategic risk issue. It raises questions around long‑term power availability, exposure to fuel and pricing shocks, planning and consenting strategy, and how energy risk is allocated contractually across ownership and operational structures.

In short, resilience is no longer just about surviving outages. It is about insulating critical infrastructure from geopolitical energy shocks. Sustainability remains vital, but the current conflict demonstrates that energy security now sits alongside decarbonisation as a primary driver of data centre strategy.

Resilience, sustainability and regulation are converging

Resilience cannot be separated from sustainability. For example, the EU’s Energy Efficiency Directive now imposes reporting and performance obligations on larger data centres, including energy usage, cooling efficiency and waste heat reuse.

While driven by climate policy, these requirements also support resilience by reducing strain on power, cooling and grid infrastructure. All of these are critical during periods of disruption. For developers, energy strategy is increasingly inseparable from resilience strategy.

What this means in practice

For those involved in developing, owning or operating data centres, the lesson is clear. Resilience, data sovereignty and energy security must be embedded at a legal and structural level, not retrofitted later.

That means:

  • Addressing resilience and power security at the site selection and planning stage.
  • Clearly allocating operational and energy‑related risk in contracts and funding documentation.
  • Treating regulatory compliance as a value‑preserving exercise, not a tick‑box.

The events in Iran may be extreme, but the signal is unmistakable. Data centres are now nationally significant assets. Their regulation, design and energy strategy are evolving accordingly.

Those who anticipate this shift will be better placed to manage risk, protect asset value and maintain trust in an increasingly uncertain world.

Cloud infrastructure was always theoretically vulnerable to kinetic warfare, but nobody had priced that risk in so far. Now that has to change

https://www.aa.com.tr/en/middle-east/iran-war-shows-data-centers-emerging-as-critical-targets/3852984

The long awaited draft Commonhold and Leasehold Reform Bill has landed!

Enfranchisement

Following the publication of the White Paper on Commonhold in March last year, the draft Commonhold and Leasehold Reform Bill landed today.

Overview: What is the bill trying to achieve?

The bill makes fundamental changes to a number of aspects of property, housing and landlord and tenant legislation; its core aim being to end the leasehold system and, by reinvigorating the model, to make commonhold the default tenure for flats.

Structure of the bill

The bill, made up of 6 parts and supported by a number of detailed schedules, attempts to deliver on the government’s manifesto commitments.

Part 1 – commonhold (core provisions of the bill)

This part rebuilds commonhold law from the ground up, repealing and replacing Part 1 of the Commonhold and Leasehold Reform Act 2002 (“the 2002 Act”).

It sets out a more structured and detailed approach to how commonhold schemes will be created, operated, and brought to an end – and of particular interest, it provides for conversion to proceed with 50% of qualifying leaseholders, rather than unanimity.

It provides detailed provisions on the Commonhold Community Statement, clarifies the functions and obligations of the commonhold association, and defines the respective rights and duties of unit‑holders and occupiers. 

In addition, the bill introduces new statutory processes allowing commonhold land to be extended, partially dismantled or developed, alongside comprehensive provisions governing financial administration, compliance mechanisms and the resolution of disputes.

Part 2 – new leasehold flats

Part 2 restricts the grant of new long residential leases of flats, save where defined exemptions apply, and establishes a statutory system of remedies where such leases are granted in breach of those restrictions.

A consultation on this opened today, seeking views from the industry and consumers on questions relating to scope, exemptions, timings, transitional arrangements, and the wider commonhold legal framework – Moving to commonhold: banning leasehold for new flats – GOV.UK

The consultation remains open until 24 April 2026 and anyone in the sector is encouraged to have their say!

Part 3 – ground rent

This part imposes a cap on ground rent in existing leases to £250pa, reducing it to a peppercorn after 40 years. 

My colleague, James Carpenter will be reporting on this separately.

Part 4 – enforcement of long leases

This part abolishes forfeiture in long residential leases and replaces it with a new, fairer, enforcement scheme.

Part 5 – estate rentcharges

This part repeals disproportionate enforcement powers applied to rentcharges.

Part 6 – general and miscellaneous

This part contains general provisions such as Crown application, power to make consequential amendments, Court/tribunal rules, regulations, extent and commencement/transitional provisions.

Schedules

These contain technical details on many aspects of the bill including:

  • permitted lease categories;
  • commonhold finance rules;
  • order for sale procedures;
  • rights to acquire or convert to commonhold;
  • financial penalties; and
  • amendments to dozens of existing pieces of legislation.

Impact of the bill

The Commonhold and Leasehold Reform Bill is not an amendment to the 2002 Act but its replacement in spirit and substance.  While the 2002 Act introduced commonhold, the bill is designed to make it work, whilst simultaneously phasing out the leasehold system.

There is a long road ahead as the bill passes into pre-legislative scrutiny and through Parliament – and the devil will most certainly be in the detail.  

More on this to follow from Forsters in the coming weeks and months.

Over 5 million leaseholders and future homeowners will benefit from stronger control, powers and protections, through the draft Commonhold and Leasehold Reform Bill published today (Tuesday 27 January), which will fundamentally rewire homeownership across England and Wales.

https://www.gov.uk/government/news/pm-were-capping-ground-rents-at-250