Is it a bird, is it a plane… or is it trespass?

Key points

  • Drone use is increasing rapidly across the UK.
  • Property owners do not own unlimited airspace above their land.
  • Low-altitude drone flights may give rise to trespass, nuisance, privacy or data protection issues.
  • Current case law remains highly fact specific.
  • As commercial drone use expands, courts may face new questions about low-level airspace rights.

Drones, airspace and property rights in England and Wales

Imagine ordering a parcel in the morning and watching it descend into your garden an hour later, delivered by drone.

This is no longer science fiction. In May 2026, Amazon became the first retailer to make drone deliveries to customers in the UK, operating its Prime Air service from a centre in Darlington under a Civil Aviation Authority trial authorisation. For one resident in Darlington, that prospect became rather more literal in July 2026, when an Amazon Prime Air drone crashed into a garden mid delivery. No one was hurt but the UK Air Accident’s Investigation Branch opened an inquiry – a reminder that “delivered by drone” can occasionally mean more than the marketing suggests.

For those accustomed to thinking of drones as toys or tools of military surveillance, the pace of this change is striking. Drones are now used routinely for surveying, infrastructure inspection, media production, and security monitoring, as well as parcel deliveries. They operate at altitudes far lower than conventional aircraft, meaning they pass not over empty sky but over gardens, farms, construction sites, and private estates.

 As their use grows, so do the questions they raise for landowners and occupiers: who controls the airspace above private land, what can a landowner do when a drone hovers uninvited, and does the law, much of it written long before the first consumer drone took flight, have adequate answers?

Although the regulatory framework is well established, the intersection of aviation regulation and private property rights remains an evolving area of law.

The regulatory framework

Drone operation in the UK is regulated by the Civil Aviation Authority, which publishes operational guidance through the Drone and Model Aircraft Code.

Under the Code, anyone flying a drone weighing 100g or more will generally require a Flyer ID. An Operator ID may also be required, including where a drone weighs 250g or more or weighs 100g or more and is equipped with a camera. Operators must generally fly below 120 metres, keep the drone within visual line of sight, and ensure that flights do not endanger people or property. Operators are also expected to respect privacy and obtain permission before retrieving a drone from private land.

The statutory framework underpinning these rules is contained primarily in the Air Navigation Order 2016, which classifies drones as unmanned aircraft and imposes restrictions on matters such as altitude limits, proximity to airports and flights near people or congested areas. Breaches may constitute criminal offences. Enforcement sits primarily with the police, who may investigate ANO breaches, and with the Civil Aviation Authority, which has powers to investigate and impose civil sanctions. Landowners or members of the public who believe a drone is being operated unlawfully can report the matter to either body, though in practice the police will often be the first port of call for incidents occurring in the course of a flight.

The Civil Aviation Act 1982 also plays an important role. Section 76 provides that no action for trespass or nuisance arises solely by reason of aircraft flying over land at a reasonable height, provided the flight complies with aviation regulations. At the same time, the Act also imposes strict liability where an aircraft causes damage or injury on the ground.

Where drones are equipped with cameras, data protection and privacy obligations arise in addition to the aviation framework which are considered below.  

Trespass and airspace rights

While aviation regulation governs how drones may be flown, the question of whether drone activity infringes private property rights is determined by the law of trespass.

Trespass to land is a strict liability tort involving unauthorised intrusion onto land. Accordingly, a claimant is not required to establish loss or damage in order to bring a claim.

The courts have long recognised that trespass may extend into the airspace above land. In Kelsen v Imperial Tobacco Co Ltd [1957], an advertising sign projecting only a few inches into neighbouring airspace was held to constitute an actionable trespass.

Similarly, in Anchor Brewhouse (Docklands Developments) v Berkley House Ltd [1987], the use of tower cranes that swung through neighbouring airspace during construction works was restrained by injunction.

These authorities demonstrate that airspace rights are capable of protection. The more difficult question is how far those rights extend vertically.

The Bernstein principle

The leading authority is almost fifty years old. In Bernstein v Skyviews & General Ltd [1978], aerial photographs of the claimant’s property were taken from several hundred feet above ground.

The court rejected the notion that landownership extends indefinitely upwards, holding instead that a landowner’s rights extend only as far as necessary for the ordinary use and enjoyment of the land and its structures.

Flights at a sufficiently high altitude will therefore not infringe property rights. However, the decision provides limited guidance in the context of modern drone technology. It does not define the lower boundary of protected airspace or identify when low-level aerial activity becomes sufficiently intrusive to interfere with land use.

The difficulty is that Bernstein predates the widespread use of small, manoeuvrable drones capable of operating close to the ground, often for extended periods and with increasingly sophisticated cameras. It is also worth noting that where overflight does not constitute trespass, affected landowners may still have recourse to the law of private nuisance, the Protection from Harassment Act 1997, or the privacy and data protection frameworks considered below.

Recent drone litigation

The courts have only recently begun to consider disputes involving drone overflight, and the emerging case law indicates that the issue is likely to remain highly fact-specific.

In MBR Acres Ltd and others v Curtin [2025], drones were flown over a commercial animal breeding facility by animal welfare activists protesting against the use of animals in laboratory research. The claimants sought an injunction preventing flights below 100 metres and restraining “persons unknown”.

Applying the Bernstein principle, the court concluded that drone flights at approximately 50 metres did not materially interfere with the use of the land and therefore did not constitute trespass. This conclusion turned on the particular facts of the case, rather than establishing any general safe altitude. The claim against unidentified operators also failed due to insufficient evidence regarding the height and frequency of the flights. The court also observed that the law of trespass cannot be used simply to prevent aerial photography where flights occur within lawful airspace.

By contrast, in Anglo International Upholland Ltd v Wainwright [2023], drones were flown over a private estate and used to gather information that facilitated physical trespass onto the land. The court granted an injunction, indicating that the purpose and consequences of drone activity may be relevant when determining whether legal relief is appropriate. The contrast with MBR Acres is instructive: it was not the overflight itself that justified relief, but the use to which the information gathered was put.

Taken together, these decisions indicate that routine drone overflight is unlikely to amount to trespass unless it materially interferes with the use and enjoyment of land. However, the position may be more complex where drones are used in a targeted or persistent manner. Repeated low level flights intended to harass landowners or disrupt lawful activity, such as farming or construction, may give rise to claims under the law of private nuisance or the Protection from Harassment Act 1997, even where the technical threshold for trespass is not met.

Privacy and data protection

Trespass and nuisance are not the only legal frameworks engaged by drone activity. Where drones are equipped with cameras, a distinct but complementary body of law applies, and landowners and occupiers should be aware of the additional remedies and protections which may be available.

The Information Commission has published guidance on surveillance technologies that expressly includes drones, emphasising the need for operators to minimise the collection of personal data and adopt a “privacy by design” approach.

Under the UK GDPR and the Data Protection Act 2018, drone footage in which individuals can be identified constitutes personal data. Complaints about unlawful data collection may be made to the Information Commission, which has the power to investigate and impose enforcement action. However, data protection law is focused on the processing of personal data and will not always provide a practical remedy where the primary concern is intrusion over land.

Beyond data protection, the tort of misuse of private information may also be relevant. Established in Campbell v MGN Ltd [2004], the tort applies where a person has a reasonable expectation of privacy in respect of information obtained or disclosed without consent. While Campbell concerned publication rather than aerial surveillance, the underlying principles may extend to drone activity. In particular, courts recognise that location and context are key, and a home or private garden will ordinarily attract a reasonable expectation of privacy. Whether drone footage of such areas will found a claim is fact specific and is yet to be determined.

Where drone gathered images are then commercially exploited, for example through publication of private or commercially sensitive activity, claims in breach of confidence may also arise. This too remains an area which is yet to develop fully in the drone context.

Key takeaways for landowners

For landowners encountering drone activity above their property, the legal position may not always be straightforward. Several practical steps may assist in assessing whether legal action is appropriate.

  1. Assess compliance with aviation rules: Flights that breach aviation regulations may be reported to the police or the Civil Aviation Authority.
  2. Gather evidence: Drone disputes are highly fact specific. Landowners should record the approximate altitude, frequency and duration of flights, as well as any disruption caused to land use or tenant operations.
  3. Identify the operator: Registration requirements may assist in identifying drone operators, which is often necessary before legal remedies can be pursued. Where the drone falls below the registration threshold, or where the operator cannot be traced through registration records, landowners may wish to record any identifying markings on the drone, note the time and direction of travel, and consider whether CCTV or other footage is available. In some cases, the Civil Aviation Authority or police may be able to assist with operator identification.
  4. Consider the level of interference: Occasional or incidental overflight will rarely justify legal action. Courts typically require evidence of persistent or intrusive interference.
  5. Consider alternative claims: Where trespass cannot easily be established, nuisance, harassment or privacy related claims may provide alternative legal routes. These alternatives can be particularly relevant where drone activity is persistent, targeted, or connected to the commercial exploitation of footage or information gathered over private land. Where drone footage captures identifiable individuals in circumstances where they have a reasonable expectation of privacy, a complaint to the Information Commission may also be appropriate.

Future developments

The Amazon Prime Air launch in Darlington is not an isolated development. It signals a broader shift towards commercial drone use at scale.

Government and industry are already testing the infrastructure required to support this. For example, Project Skyway has trialled the concept of a dedicated drone corridor across parts of England, designed to enable drones to operate safely beyond the visual line of sight of their operators over long distances. At a regulatory level, the Civil Aviation Authority has also set out a roadmap intended to allow routine commercial delivery drone operations beyond visual line of sight by 2027, paving the way for more widespread commercial use, including delivery services.

If these developments are implemented at scale, this could lead to regular and predictable drone traffic over private land, rather than the occasional or incidental overflight considered in current case law.

This raises questions that existing law is not designed to answer directly. While the Civil Aviation Act 1982 protects overflight at a “reasonable height”, that framework developed with conventional aircraft in mind, not frequent, low level drone activity operating on commercial routes. If such activity becomes sufficiently regular or intrusive, landowners may seek to characterise it as nuisance rather than relying on trespass alone.

While current case law suggests that routine overflight will not amount to trespass (unless it materially interferes with the use of land or forms part of a broader unlawful activity), systematic and frequent drone activity may test the boundaries of nuisance and airspace rights.

Therefore, the Amazon parcel descending into a Darlington garden is, in legal terms, only the beginning. As drone deliveries move from novelty to normality, disputes about low level airspace are likely to become increasingly common. The question for the courts, and perhaps eventually Parliament, will be how to strike a balance between the rights of private landowners and the economic and social benefits of embracing new technologies.

Until then, landowners may find themselves looking upwards more often than they used to. What was once largely empty airspace is becoming increasingly busy, and the law is still working out exactly where the boundaries lie.
What is the current outlook for the UK property market?

Red post box

A guide for Americans buying a UK home: legal and tax planning considerations

Looking to relocate or invest in residential property in the UK? In this series we share our insights on the current UK market for US buyers.

Find out more

Property experts from across the industry agree that while many areas of the UK residential property market are slowing in light of recently increased costs of finance and wider political concerns in general, trophy assets continue to be a popular with international buyers, both as a place to call home and for investment purposes.  For US buyers, demand for UK residential property, and London in particular, has proved notably resilient. While recent changes to the UK’s non‑dom regime have prompted some international purchasers to reassess their position, US buyers have generally been less impacted. In Prime Central London, US buyers continue to be drawn to high‑quality apartments, period houses and landmark developments that combine heritage value with modern living, with schemes such as The Whiteley and 1 Mayfair attracting American buyers seeking a London home to live in when spending time in the UK, whether or not they ultimately relocate here. Given the new FIG regime, there has also been a marked increase in interest in renting super prime properties, particularly given the Stamp Duty Land Tax and Inheritance Tax implications of owning a property.
Potential political changes

Despite tax changes, it is hoped that Prime Central London property will remain attractive to foreign purchasers given values today in some cases are 25% down on pre-Brexit prices in real value terms making for a good long-term investment, this is in spite of changes over the years to SDLT, which have included:

  • The introduction of a surcharge of 2% for non-UK resident purchasers completing on purchases from 1 April 2021.
  • A surcharge of 3% introduced in April 2016 for purchasers who already owned a residential property anywhere in the world (and were not replacing their main residence) at the time of completion.
  • An increase in the above 3% rate to 5% introduced on 31 October 2024.
  • A “high value council tax surcharge” to be implemented in April 2028, which will lead to a charge of between £2,500-£7,500 p.a. for properties over £2m.

This means that SDLT rates for individual purchasers can now be as high as 19%.

Particular interest from the US

In terms of the international marketplace, Knight Frank continue to see steady interest from US-based buyers, with demand coming from established wealth centres across both the East and West Coast. While some buyers have repositioned domestically in recent years, prime city markets are showing renewed resilience, particularly where supply remains limited and pricing has adjusted.

Jason Mansfield of Knight Frank, Head of US Residential comments: 

“Although we support clients with their property needs across the United States, New York remains the primary destination for many of our international buyers. Despite broader economic uncertainty, pricing has held steady, rental values continue to rise, and constrained inventory is underpinning overall resilience. Demand remains diverse, and the city continues to provide the long‑term stability and depth that many of our clients seek.

Los Angeles is also demonstrating notable resilience at the top end of the market. While the past year brought meaningful challenges – including tax changes, higher insurance costs and the impact of last year’s fires – activity has remained robust. Sales above $30 million have been strong, and although some buyers initially explored moves to lower‑tax states during Covid, many are now returning. Pricing is becoming more realistic, new wealth segments are active, and several key neighbourhoods appear well positioned as we move through this year.”

Comparatively, the UK still remains attractive due to its lower holding costs, the current low exchange rate, a great education system and other niche factors. We are, for example, seeing instructions from US clients with an interest in British history, acquiring diverse properties from listed country estates to apartments in very high end Central London conversions where the historical importance of the property is a unique draw. These attractions are however increasingly set against concerns over high borrowing costs both for owner occupiers and those with investment properties, particularly as these rising costs cannot be offset against income tax.

Paddy Dring of Knight Frank, Global Head of Prime Sales and Private Office comments on Americans in London:

“In recent years, the profile of international buyers in Prime Central London has shifted subtly, reflecting a market attuned to wider global dynamics. Americans have strengthened their position as the leading overseas purchaser group, rising from 9.4% in 2023 to 13.1% in 2025. Demand from China has eased slightly – from 10.9% to 8.6% – while interest from France and Italy has fluctuated but remained consistently engaged, underpinning an ongoing appetite for lifestyle-driven acquisitions.

Taken together, these movements point to a market that is recalibrating around buyers who prioritise stability, quality, and long term fundamentals. Despite geopolitical uncertainty and evolving tax environments worldwide, London continues to stand out for its transparency, liquidity and reliability – attributes that international purchasers consistently value. These qualities reinforce its status as a steady anchor within the global luxury landscape.”

UK-US cross border issues

Against this backdrop it is important to draw attention to the specific US-UK cross border issues that may arise from US connected persons owning UK property. It is essential to incorporate these UK assets into an individual or family’s wider tax, estate and wealth plans.

We explain some of the key crossborder issues at play and reveal the planning options available to protect against these risks.

Disclaimer

This article reflects the law as of September 2026. The circumstances of each case vary and this note should not be relied upon in place of specific legal advice.

What tax and estate planning considerations are there when buying UK property?

In the next chapter we cover everything from UK inheritance tax to taking out a mortgage, and life insurance to capital gains tax.

Read the next article

Buying a UK property: What asset protection options are there?

A guide for Americans buying a UK home: legal and tax planning considerations

Looking to relocate or invest in residential property in the UK? In this series we share our insights on the current UK market for US buyers.

Find out more

Use of trusts

While the use of trusts to hold UK residential property can potentially offer some degree of asset protection when compared to outright personal ownership, this protection may not be as robust as clients would like. In the event of a divorce, for instance, trust assets can be considered a financial resource available to the spouse who is a beneficiary (although this will depend on the terms of trust, distribution patterns, etc.) and the trust may even be treated as a “nuptial settlement” if it is settled by one or both of the couple, or by a third party for their benefit. If a court finds the trust is a nuptial settlement (which is comparatively rare but not unheard of) it will have extensive powers to change the terms of the trust, remove/replace trustees, order distributions, etc. This is in stark contrast to the position in the US, where trusts are generally robust and immune from variation.

The use of trusts might also be unattractive from a tax perspective. For instance, the value of the property would suffer an IHT charge of up to 6% every ten years while it was held in trust. The property would also continue to form part of the estate of the settlor (so be subject to IHT on his or her death) unless he or she was irrevocably excluded from benefit. Excluding the settlor from benefit is unlikely to be practical if he or she wishes to occupy the property. Furthermore, holding the property in trust would give rise to reporting obligations for the trustees, who would need to report the existence of the trust and details of its beneficiaries to HMRC through the Trust Registration Service.

As a result, there will only be very limited scenarios in which trust ownership will be appealing. Generally speaking, direct personal ownership will be the preferred route for the family home.


Protecting assets from separation or divorce – Dickon Ceadel, Family Partner:

Nuptial agreements

A pre-nuptial or post-nuptial agreement offers the best degree of protection for UK property on divorce. Parties are able to define marital property (which is to be shared) and separate property (to be ringfenced) on divorce and can also seek to prescribe levels of maintenance payable on separation. Whilst pre-nups are not automatically enforceable in England and Wales, provided the agreement meets the parties’ respective needs, and those of any children, its terms should generally be upheld.

There are many reasons why people have a nuptial agreement, including;

(i) if there is an actual or expected disparity between the wealth of the spouses;
(ii) there are assets which have been in one of the couple’s families for generations that they would like to protect on divorce, in order that future generations can benefit and
(iii) if it is not a first marriage and a party wants to preserve assets for children of a previous marriage.

The aim of nuptial agreements is to provide certainty and security if the marriage did breakdown, and more power to a couple to make arrangements for the future, rather than leaving everything to be determined by the court. Above all else, a pre-nuptial or post-nuptial agreement can save acrimony and potentially significant costs if there were a divorce in the future.

Pre-nups and post-nups will be familiar territory to many US-connected clients, but there are some additional considerations and differences that they will need to be aware of on moving from the US to the UK. English nuptial agreements are not automatically enforceable like pre-nups in the US, but are instead afforded differing weight depending on a number of factors. Case law states that the starting point is that nuptial agreements should be upheld so long as they must meet certain conditions including;

(i) the agreement been entered into freely;
(ii) each party has taken independent legal advice;
(iii) there has been full financial disclosure by both parties; and
(iv) agreement is fair. This element of fairness is the second main differentiator between UK and US pre-nups; if a US pre-nup is in place, it must satisfy the principles of fairness to be upheld in England.

It would be wise for any clients that are moving from the US to the UK to have their arrangements reviewed by a specialist English family lawyer and revised or supplemented, if necessary, to provide more robust protection against claims on divorce. Alternatively, if a nuptial agreement is not in place, a move to the UK or an investment in UK property may provide the impetus to negotiate a post-nup.

Cohabitation

There can also be a risk of claims against property on the separation of unmarried cohabitees. While cohabiting couples currently have no automatic legal status on separation, (there is no such thing as common law marriage in England), there are a number of means through which one party can make a claim against the other with respect to property. Moreover, the Labour Government has now completed its consultation on reforming the rights of unmarried couples, with proposals for enhanced protections for cohabitants under consideration. It is therefore important to note that this is a developing area of law and the legal position may change in the coming years.

However, as things stand in England and Wales, cohabitation is a patchwork quilt of potential claims that can call on various different areas of law, including property, family, trust and children law, to make a claim.

For example;

a) Claims for the benefit of children – The court could make a settlement or transfer of property order, to provide a home for the child for their minority (NB: Any capital awarded to purchase a property is likely to be held in trust until the child’s majority or the end of full-time education, when it will revert to the payer).
b) Trusts of land – One party may be able to rely on actions during the course of a relationship (e.g. conversations, oral agreements, regular payments towards outgoings in relation to the property etc.) to establish a beneficial interest pursuant to an implied, resulting or constructive trust. The latter is most relevant in the domestic context. Alternatively, a party can rely on proprietary estoppel to claim a beneficial interest.

They must show:

(i) an assurance on the part of the other party (e.g. leading them to believe they will have some right in relation to the property)
(ii) that they relied on the assurance to their detriment; and
(iii) that it would be unconscionable for the other party to deny them the right they expected to have.

Cohabitation agreements can protect against these risks. They allow parties to regulate the terms of their cohabitation, providing clarity both during the course of the relationship and in the event that it should break down.

The agreement would incorporate or be accompanied by a declaration of trust in relation to any real property, confirming the parties’ respective beneficial interests. The agreement can also deal with a wider range of issues, including how household expenses are to be split; what happens if one party wishes to sell the property and the other does not; financial support during and after cohabitation; and living arrangements and financial provision for children.

Security and clarity of such a kind is extremely beneficial to a couple if the relationship breaks down in the future.

Conclusion – How we can help

The UK and London in particular remains a leading destination of choice for wealthy international families.

While there will often be additional challenges for US-connected clients, these can be navigated with the right team on board. Our private client team have UK-US cross border specialists experienced at guiding US connected clients through their planning. Along with our strong network of expert contacts, we are on hand to provide comprehensive support.

Our definitive guide to nuptial agreements

Want to know more?

Speak to our team of expert lawyers

Contact us

Your guide to US-UK cross-border planning

Understand the issues, avoid the traps, and discover ways to plan ahead in our Navigating the Atlantic guide for US-connected individuals and families.

Find out more

What tax and estate planning considerations are there when buying UK property?

A guide for Americans buying a UK home: legal and tax planning considerations

Looking to relocate or invest in residential property in the UK? In this series we share our insights on the current UK market for US buyers.

Find out more

Exposure to UK inheritance tax

The acquisition of UK real estate by a person who is not a ‘long term resident’ of the UK (LTR) will always come with an increased exposure to UK inheritance tax (IHT). The value of UK property in a person’s estate will be subject to IHT at a flat rate of 40% on death if and to the extent that it exceeds the deceased’s available ‘nil rate band’ amount of up to £325,000. This may come as a shock to clients from the US, where the amount that can pass free of Federal estate tax is $15m in 2026!

In the past, individuals who were only exposed to IHT on UK assets would have been advised to acquire UK real estate through a non-UK registered holding company, which would serve as a “situs blocker” and protected the value of the property from IHT. However, following the introduction of anti-avoidance legislation in April 2017, shares in a non-UK registered company will now be treated as UK assets for IHT purposes (so will be exposed to IHT, regardless of the deceased owner’s LTR status) if and to the extent that their value reflects the value of underlying UK residential property interests.

Taking out a mortgage

The options for mitigating this IHT exposure are now very limited. In most cases, the only option will be to purchase the property with the benefit of a commercial mortgage, which should be deductible against the value of the property for IHT purposes. Of course, this comes at the cost of paying interest to the lender, and whether this is worthwhile will vary from case to case.

Where US persons are taking out mortgages to fund purchases, there are some extra considerations to be taken into account.

Borrowing from individuals (e.g. friends or family) or non-UK resident trusts offers less IHT protection when viewed holistically because, although the debt should be deductible from the borrower’s estate for IHT purposes (subject to various legislative conditions being met), the benefit of the debt will be subject to IHT in the lender’s hands. This was another of the changes introduced in April 2017.

As explained by James Rose, a Private Banker at Coutts & Co:

“For US people, getting a UK mortgage can present a number of issues. Many banks will struggle to lend to people whose income isn’t denominated in GBP and will want to see the income being received into a UK bank account. These issues are further amplified for HNW individuals, who are often not salaried individuals but instead have complex income streams. In these circumstances, it may be better to find a lender who can adopt a more pragmatic approach and potentially consider the client’s wider asset base to support the application. Furthermore, while many US clients may want to consider taking an Interest-Only mortgage for tax planning purposes, a number of changes to mortgage regulations over the last decade mean that few banks are willing to offer these any more. Nonetheless, US clients should be careful about taking a “flexible” mortgage product (such as those which you repay and redraw) and should seek specific tax advice as these products can have unintended US tax consequences as well. Overall, it is worth looking for a Private Bank or specialist mortgage lender who can take into account more complex client circumstances as well as engaging with a tax adviser who understands both countries “tax regimes.”

Life insurance

Given the limited scope for IHT planning and increasing cost of mortgages driven by higher interest rates, many clients will choose to accept the IHT burden and, instead, take out life insurance to cover the liability that will arise on their death. If they do this, they should be advised to take out the policy through a life insurance trust (or assign the benefit of the policy to a trust) to prevent the proceeds themselves being subject to IHT.

Christiaan van den Hout of Vie International explains that:

“US clients may already be familiar with holding life insurance as a financial planning tool.

If a US person has relocated to the UK, life insurance policies will now need to deliver a solution that is effective from a tax, legal and payout perspective considering both UK and US jurisdictions.

We find that clients who already hold life insurance policies benefit from a policy review to ensure the design and structuring is still in their best interest.

Several highly rated US domestic insurers will accept overseas residents, including both US citizens and also non-US citizens with US ties.

Policy design, funding and structuring options are flexible so the clients’ needs are well served, particularly for the buyers of London’s most sought after and valuable homes.

A US sourced policy, designed and structured in a dual UK/US compliant trust can deliver robust protection and value for US-connected clients, while providing financial clarity that there is a plan to settle their UK inheritance tax liability in a timely and tax efficient manner.”

But US citizens and residents will also need to ensure that the trusts they create will take the form of US irrevocable life insurance trusts (“ILITs”).

Dina Kapur Sanna of Day Pitney LLP comments that:

“Assuming the ILIT is properly drafted and administered, at the death of the donor-insured, the insurance proceeds will not be includable in the insured’s taxable estate and will also be exempt from income taxes.

If an insurance policy is transferred to the trust or purchased by the trust and is completely owned by the trust, cash gifts can be made to the trust each year to pay the premiums without the ownership of the insurance being attributed to the insured. This can keep the full death benefit of the policy out of the estate of both the insured and the surviving spouse; provided, however, if the policy is transferred to the trust, there is a 3-year survival requirement for the proceeds to escape estate tax on the death of the donor.

The gifts to the trust can be designed to qualify for the $19,000 annual gift tax exclusion through what are sometimes called “Crummey” withdrawal powers exercisable by the beneficiaries (usually the spouse and children, or in the case of a two-life policy, by children and more remote descendants).

It should be noted that, if life insurance is taken out with the express purpose of paying off a mortgage, the ILIT will not protect it from US estate tax. The ILIT must be independent of the residential purchase, and the death benefit must be paid to the beneficiaries (not the bank) after the death of the insured.”

Wills

Clients who acquire UK real estate should also be advised to consider putting in place a UK will. For married couples, the UK will should be structured in a way that allows access to the spouse exemption from IHT, so the tax liability can be deferred until the second death. While this can potentially be achieved in a foreign will, the added benefit of having a UK will in place is to facilitate the administration of the UK estate on death.

In particular, to obtain probate of a foreign (e.g. US) will in the UK, the Probate Registry will require an affidavit of foreign law (provided by US counsel) confirming the validity of the will as a matter of local law and who is entitled to administer the estate. This gives rise to an additional administrative hurdle (and associated costs) for the executors that would not arise if there was a local will in place. Having said that, if primary probate is granted in the US, the Probate Registry will generally accept a court-exemplified copy of the US will to probate in the UK without an affidavit. But this option has its own disadvantages, including the inevitable delay in administering the UK assets.

Capital gains tax on the family home

For UK capital gains tax (CGT) purposes, gains realised on the disposal of a person’s main home benefit from 100% relief, assuming the property has been that person’s main home throughout the period of ownership. This is not the case for US income tax purposes, where only the first $250,000 will be exempt and the balance will be subject to tax. This US tax overlay can cause the UK relief to be wasted.

Therefore, in the case of a couple with one US spouse and one non-US spouse, it will generally be most tax efficient for the main home to be owned solely by the non-US spouse. But where the US spouse is funding the acquisition of the property, it’s not that simple! Due to the absence of an unlimited spousal exemption from US gift tax on gifts to non-US citizen spouses, the gift itself could have adverse US transfer tax consequences. To address this, the US spouse might consider making annual gifts of fractional interests in the property to the non-US spouse. Under current rules, the US spouse can make gifts of up to $194,000 to the non-US spouse each year free of US Federal gift tax. These regular gifts can add up over time to improve the CGT position.

Buying a UK property: What asset protection options are there?

Understand how trusts, nuptial agreements and cohabitation agreements can offer you protection.

Read the next article

Right to Work checks are changing from 1 October 2026: What should employers be doing now?

From 1 October 2026, the scope of the Right to Work regime is set to expand significantly. The changes are particularly important for businesses that engage individuals outside a traditional employer-employee relationship, or which rely on contractors, subcontractors, outsourced service providers or online platforms.

The Home Office published an updated draft Employer’s Guide on 11 September 2026, intended to come into force on 1 October 2026. The reforms expand the Right to Work Scheme beyond conventional employees and introduce potential liability further up certain contractual chains.

For businesses, the key practical message is that Right to Work compliance can no longer be considered solely as an HR onboarding issue. Businesses will need to look more broadly at how they engage individuals, how their supply chains operate and, importantly, who is actually carrying out work on their behalf.

A quick reminder: What is a Right to Work check?

A prescribed Right to Work check should be undertaken before work starts. When conducted correctly, the check provides a statutory excuse against a civil penalty if the individual is subsequently found to be working illegally.

Depending on the individual’s circumstances, the prescribed process may involve a manual document check, the Home Office online service or an eligible digital verification service provider (DVSP). Employers should also check that the individual is permitted to undertake the particular work in question, including any applicable restrictions.

The important point is that compliance is not simply about asking to “see a visa”. The objective is to complete the correct prescribed check and retain appropriate evidence of it.

What is changing?

One of the most significant changes from 1 October is the proposed expansion of the regime beyond conventional employees.

The Scheme is set to extend to certain arrangements involving:

  • workers engaged under a worker’s contract;
  • individual subcontractors within contractual chains; and
  • certain online matching services which connect individual service providers with clients or customers.

For businesses which have historically regarded these arrangements as sitting outside the traditional Right to Work framework, this warrants careful attention.

Look beyond your immediate workforce

Perhaps the most important development for businesses is the introduction of extended liability.

Under the new regime, potential exposure may extend further up a contractual chain, rather than resting only with the organisation that has a direct relationship with the individual performing the work.

The arrangements that businesses should be considering include contracting chains, online matching arrangements and substitution provisions.

Take a relatively straightforward outsourcing arrangement:

ClientCo → ServiceCo → individual worker/subcontractor

Historically, ClientCo may have assumed that Right to Work compliance was entirely a matter for ServiceCo. Under the extended liability provisions, businesses will need to look more carefully at the contractual structure and arrangements in practice before reaching that conclusion.

A useful question for businesses to ask is therefore:

Do we know who is actually performing the work under our contracts?

This is particularly relevant where subcontracting or substitution is permitted.

Don’t assume outsourcing the check outsources the liability

Digital Right to Work checking is also increasingly important. Registered Right to Work DVSPs may be used in prescribed circumstances, including for eligible British and Irish passport or passport card checks.

However, using a third-party provider does not automatically transfer responsibility away from the business. Employers still need to understand what has been checked and ensure that the required evidence is retained.

Businesses should therefore review not only whether they use a digital provider, but also how that process fits within their wider Right to Work compliance framework.

Avoid creating a discrimination problem

Businesses should also ensure that increased scrutiny of Right to Work compliance does not inadvertently result in discriminatory recruitment practices.

Processes should be applied consistently. Businesses should not select individuals for checks because of nationality, race, appearance or assumed immigration status, and should not insist on one method of demonstrating a Right to Work where another prescribed route is available.

One practical example is the use of share codes. A share code is an online code generated by an individual that allows an employer to access their Home Office immigration record and confirm their right to work in the UK. The employer uses the share code, together with the individual’s date of birth, to carry out an online right to work check. Businesses should not design their recruitment process on the assumption that everyone will be able to provide a share code. British and Irish citizens ordinarily use eligible original documents or an appropriate digital verification service instead.

Does everyone need a new check on 1 October?

No. Businesses should avoid unnecessary repeat checking of their entire existing workforce.

The relevant questions will instead include whether a new engagement is commencing, whether an existing individual’s repeat check falls due, or whether an arrangement falls within the expanded regime from 1 October.

This distinction should help businesses focus their compliance resources on the areas where the changes genuinely create new risk.

Five practical steps to take now

With 1 October approaching, businesses should consider the following:

1. Map your workforce

Don’t stop at employees. Identify how the organisation uses workers, individual contractors, subcontractors, agency labour, outsourced services, online platforms and arrangements which permit substitutes.

2. Map your contracts

Review agreements for personal service requirements, substitution rights, subcontracting provisions, staffing obligations and supply-chain arrangements. Consider whether online matching or platform arrangements are used anywhere within the business. 

3. Audit your Right to Work processes

Consider who conducts checks, which checking method is used, what evidence is retained, where it is stored and who is responsible for monitoring expiry dates. Businesses should also understand when the Employer Checking Service may be required.

4. Review supplier arrangements

Where individuals are supplied through third parties, consider whether contractual arrangements adequately deal with Right to Work compliance. This may include checking obligations, evidence and assurance requirements, notification provisions, audit cooperation, warranties, indemnities and appropriate obligations flowing down to subcontractors.

5. Train the people who need to know

The changes should not be viewed as relevant only to HR. Recruitment, onboarding, procurement, compliance, operational teams and hiring managers may all need to understand how the revised regime affects their role.

The key takeaway

The most significant shift on 1 October is one of scope. Right to Work compliance is becoming relevant to a wider range of working and contractual arrangements.

Businesses should therefore look beyond their payroll and ask three practical questions:

Who is actually working for us or providing services? Who engages them? And are we satisfied that the appropriate Right to Work checks and contractual protections are in place?

Taking the opportunity now to map those arrangements and review existing processes should put businesses in a stronger position when the new regime takes effect.

How we can help

Forsters can help employers assess how the reforms affect their workforce and contractual arrangements, review and strengthen existing Right to Work processes and supplier arrangements, and provide tailored Right to Work training for HR, recruitment, procurement, compliance and operational teams.

Biodiversity net gain: 2026 exemptions and opportunities for landowners

Introduced by the Environment Act 2021 and, in large part, taking effect in February 2024, the biodiversity net gain regime (BNG) has introduced a new framework for both developers and landowners to engage with the provision and delivery of BNG.

How the BNG regime works

The biodiversity gain objective of the Act will be met when, in relation to development for which planning permission is granted, the post-development biodiversity value exceeds the pre-development biodiversity value of the on-site habitat by at least 10%.

The latest exemptions

There are a number of statutory exemptions to the BNG requirements, most recently updated in August 2026. Where a development subject to a planning application satisfies the criteria of an exemption, that development will not be required to comply with the BNG requirements introduced by the Act.

The most recent amendments to the BNG exemptions provide that:

  • BNG does not apply to planning applications for developments where the site area within the red-line boundary is 0.2 hectares or below
  • BNG does not apply to short-term developments if the whole development is temporary or planning permission is granted for five years or less.

Both of the above exemptions are not applicable where priority habitat is affected by the proposed development.

The self-build and custom-build exemption no longer applies to new planning applications made on or after 6 August 2026. This exemption has now been revoked.

Opportunities for off-site delivery

A notable exemption is for developments creating or enhancing habitats solely, or mainly, for the purpose of fulfilling the BNG planning condition for another development.

The requirement for developers to seek to secure the 10% gain needed to meet the BNG objective off site, where it is not possible to achieve it on site, means that many landowners have sought to dedicate parts of their land as off-site gain areas.

While there are a number of statutory obligations which come with designating land in this way, most notably the requirement for the gain to be maintained for a period of 30 years, it does provide an opportunity for landowners to diversify land which may previously have not served an active ecological purpose.

BNG for nationally significant infrastructure projects

The BNG regime will apply distinctly to the nationally significant infrastructure project (NSIP) regime, with an adapted framework of obligations tailored to this specific type of development.

BNG is targeted to come into effect on 2 November 2026 for NSIP projects. This regime will focus on the BNG boundary, not all of the habitats within the entirety of the area subject to the development consent order.

These projects will be able to use either on-site or off-site delivery as a starting point, meaning that there may be greater focus on off-site opportunities from the outset by the developers delivering these projects.

What this means in practice

Recent changes to the BNG regime and the forthcoming extension to nationally significant infrastructure projects may create further opportunities for landowners considering off-site habitat delivery.

However, any arrangement should be assessed carefully in light of its long-term management requirements, commercial terms and impact on wider estate objectives.

How environmental data and natural capital can protect rural estate value

Environmental regulation is evolving rapidly. Biodiversity net gain has already demonstrated how quickly environmental considerations can move from policy discussion to legal requirement and commercial reality.

Alongside this, frameworks such as the Taskforce on Nature-related Financial Disclosures (TNFD), the emergence of nature-related reporting requirements under the European Sustainability Reporting Standards and the growing focus of investors on nature-related risk all reflect a broader shift in market expectations.

While the precise regulatory landscape continues to evolve, the direction of travel is increasingly clear: environmental performance is becoming more relevant to the way land is owned, managed and valued.

Why environmental data matters

The legal sector is advising an increasing number of landowners, farmers and estates on natural capital projects, biodiversity initiatives, development opportunities and broader estate-management strategies.

A common theme runs through all of these conversations. The estates best placed to respond to change are those that understand, measure and monitor their natural capital assets and can demonstrate how those assets are being managed over time.

The value of Wildlife Estates accreditation

This is where Wildlife Estates accreditation has particular significance.

The immediate value of accreditation is not simply environmental recognition. Rather, it provides a structured framework for identifying, measuring and monitoring natural capital assets across an estate. The baseline surveys, ongoing monitoring and governance processes embedded within the accreditation create robust and accessible data about the condition, management and resilience of the land.

From a legal perspective, that evidence base is set to become increasingly important. As environmental regulation develops, landowners are likely to face greater scrutiny regarding biodiversity, water resources, habitat condition and wider environmental impacts.

Those able to evidence a clear history of responsible management and informed decision-making are likely to be better positioned than those unable to demonstrate the condition of their assets.

This may be relevant not only when seeking investment or support through environmental schemes for resource management, but also in the context of supply-chain requirements, financing arrangements, estate transactions and a range of other commercial decisions where environmental risk is becoming a material consideration.

Investors are increasingly seeking opportunities that can demonstrate measurable environmental outcomes alongside financial returns. Equally, businesses throughout the food and rural supply chains are facing growing pressure from customers, regulators and financiers to understand environmental risks within their operations.

As nature-related disclosure frameworks such as TNFD continue to gain traction, the ability to produce reliable environmental data and demonstrate a structured approach to land management is becoming increasingly valuable. Accreditation provides an independent and credible framework that can help landowners evidence performance and engage confidently with these stakeholders.

Turning evidence into opportunity

Importantly, good data creates opportunity. Whether the objective is attracting inward investment, participating in natural capital markets, securing green finance or demonstrating strong supply-chain credentials, opportunities may be more readily accessible where environmental information is already available, independently verified and capable of withstanding scrutiny.

Accreditation helps estates become investment-ready by generating the information, governance processes and supporting evidence that investors, lenders and counterparties increasingly expect to see.

Perhaps most importantly, Wildlife Estates accreditation enables landowners to move beyond compliance and towards resilience. As legal frameworks evolve and markets place greater emphasis on environmental performance, transparency and risk management, accreditation provides a practical means of protecting asset value, evidencing responsible stewardship and demonstrating that an estate is prepared for future change rather than reacting to it.

Viewed through that lens, Wildlife Estates accreditation is not simply a recognition of good environmental practice. It is a practical asset-management tool, helping estates protect value, demonstrate resilience and position themselves confidently for the legal, commercial and regulatory challenges ahead.

What this means in practice

Reliable environmental data is becoming increasingly valuable across estate management, funding, investment and natural capital opportunities. Estates that can evidence the quality and performance of their natural assets are likely to be better positioned to respond to future opportunities and regulatory change.

Environmental schemes, inheritance tax and succession planning for rural estates

For many farms and estates, wildlife management and habitat enhancement are nothing new. Long before biodiversity net gain (BNG), carbon markets and ecosystem services became part of the rural vocabulary, landowners were managing woodlands, wetlands, grassland, game habitats and other environmental assets as part of responsible estate stewardship.

What has changed is that activities which many farms and estates were already undertaking for wildlife, habitat management and wider stewardship purposes are increasingly capable of generating income in their own right. BNG, nutrient neutrality, carbon projects and other environmental schemes are creating commercial opportunities that simply did not exist a few years ago.

The scale of activity is already considerable. More than 50 Landscape Recovery projects have been reported as having been developed across England, covering approximately 240,000 hectares. At the same time, wildlife and habitat management schemes continue to expand across both farms and larger estates.

Against that backdrop, environmental schemes are increasingly becoming part of a much wider discussion about estate resilience, inheritance tax (IHT) and succession planning.

A changing IHT landscape

The restrictions to Agricultural Property Relief (APR) and Business Property Relief (BPR) from 6 April 2026 have led many farming and landed estate families to revisit long-established succession plans. For some, the changes have raised questions about how future IHT liabilities will be funded without selling land or weakening the underlying business.

The debate is often framed as a tax issue, but in reality it is much wider than that. Succession planning is fundamentally about ensuring that a business remains viable and that ownership can pass successfully between generations.

Many farms and estates are therefore considering how environmental schemes might contribute to that objective. The attraction is obvious. Environmental projects may generate long-term income without requiring the underlying land to be sold.

In the right circumstances, that income may help support future IHT liabilities, fund capital expenditure or provide for family members who are not directly involved in the core business. Taken together, these factors are increasing pressure on cash flow and making long-term sources of income more attractive than they may previously have been.

Greater tax certainty

One of the difficulties with environmental schemes has been uncertainty over their tax treatment.

HMRC’s publication of its Technical Note on Ecosystem Services in May 2026 has provided welcome clarity. The guidance addresses biodiversity net gain, nutrient neutrality, woodland carbon and peatland schemes and explains HMRC’s approach to their taxation.

Perhaps the most interesting aspect of the guidance is HMRC’s recognition that environmental income will often arise within the context of a wider rural business. In many cases, receipts may be treated as trading income rather than passive investment returns, although the precise treatment will depend on how the arrangement is structured. Until then, there had been significant uncertainty, making it difficult for farms and estates to plan with confidence.

This is highly relevant to the ability to claim BPR, which applies only to businesses that are wholly or mainly trading. Prior to the guidance, many landowners were concerned that replacing farming income with environmental income might weaken claims for BPR by making the business appear more investment-based in nature, with dire IHT consequences.

The guidance also confirms that receipts will generally be treated as income rather than capital and so potentially subject to higher rates of income tax than capital gains, save in more limited situations where a payment genuinely represents compensation for the permanent sterilisation of land.

Importantly, the extension of APR to certain qualifying environmental management agreements has also reduced concerns that participation in environmental schemes might automatically jeopardise IHT relief.

Thinking beyond income

While much attention has focused on the potential financial returns, the more interesting question is often whether a scheme aligns with the long-term objectives of the estate or farm.

Many environmental agreements involve commitments lasting decades. Statutory off-site BNG gains must generally be maintained for at least 30 years and some schemes may have an even longer horizon. That means these projects should be viewed not simply as income-generating opportunities but as succession-planning decisions.

Families should therefore consider:

  • Whether future generations will welcome the restrictions being imposed on land use.
  • Whether flexibility is being surrendered.
  • Whether alternative opportunities are being given up.
  • How environmental income will be shared.
  • Whether existing trusts, partnerships or governance structures remain appropriate.

For many farms and estates, the real value of environmental schemes may lie not in the headline payment, but in their ability to strengthen the long-term resilience of the business while supporting wildlife and environmental objectives that are already central to the farm’s or estate’s identity.

Looking ahead

The most successful farms and estates have always taken a long-term view. Wildlife management, habitat enhancement and environmental stewardship frequently involve timescales that extend well beyond a single generation. Environmental markets are no different.

The most successful projects are unlikely to be those that simply generate the largest environmental payment. Instead, they will be the projects that enhance wildlife and habitats, support the wider business, preserve flexibility where possible and sit comfortably within the family’s long-term succession plans.

For many farms and estates, environmental schemes are no longer simply about conservation. Increasingly, they are becoming part of the broader conversation about how land, businesses and stewardship responsibilities are passed to the next generation.

What this means in practice

Before entering an environmental scheme, landowners should consider how the arrangement supports the estate’s long-term objectives, succession plans and future flexibility. Environmental income can be attractive, but the most successful projects are often those that complement the wider business and stewardship ambitions of the estate.

Checkmate – managing a counterparty’s insolvency

Chess pieces lying down having been knocked over

Checkmate – your essential guide to commercial disputes

This series of articles provides a valuable point of orientation to help readers navigate uncertainty with greater confidence.

Read our Checkmate series

Understanding your options when a customer, supplier or business partner fails

While businesses typically spend considerable time assessing the financial strength of customers, suppliers and contractual counterparties before entering into a relationship, insolvencies can occur unexpectedly. Even a seemingly stable trading partner can encounter financial difficulties with little warning.

When a key customer, supplier, contractor or joint venture partner enters insolvency proceedings, the commercial consequences are often both immediate and significant. Deliveries may stop, payments may be delayed, projects curtailed, and longstanding commercial relationships become rapidly contentious.

In such circumstances, businesses are often required to make important decisions before obtaining detailed legal advice. Understanding the issues likely to arise – and the potential options available – can help organisations respond quickly, protect their position and minimise disruption.

In this feature, we consider some of the most common disputes and strategic considerations that arise when a counterparty becomes insolvent.

This article forms part of our Checkmate Series – your essential guide to commercial disputes, a collection of practical insights designed to help businesses navigate common dispute scenarios with clarity and confidence. Explore the full guide here.

What does insolvency actually mean?

The term “insolvency” covers a range of formal procedures, each designed to deal with a company facing financial difficulties.

These include:

  • Administration
  • Liquidation
  • Company Voluntary Arrangements (CVAs)
  • Restructuring Plans
  • Receivership

The implications for creditors, suppliers, customers and contractual counterparties can differ considerably depending on the process involved.

A common misconception is that an insolvent company automatically ceases trading. In reality, businesses often continue operating during certain insolvency processes, particularly administration or a restructuring exercise. Understanding the nature of the insolvency process frequently forms the first step in assessing your options.

The warning signs of financial distress

Formal insolvency proceedings are often preceded by signs of financial difficulty.

Potential indicators include:

  • Persistent late payment of invoices
  • Requests for extended payment terms
  • Reduced communication from senior management
  • Sudden changes in purchasing behaviour
  • Delays in fulfilling contractual obligations
  • Staff departures or operational disruption
  • Reports of creditor pressure

Identifying warning signs early may allow for businesses to reduce exposure, secure outstanding payments or reassess ongoing contractual commitments before the situation deteriorates.

Can you terminate a contract?

One of the first questions organisations ask following a counterparty’s insolvency is whether they can bring the contractual relationship to an end.

The answer will often depend on the terms of the underlying agreement and the nature of the insolvency process involved.

Many commercial contracts contain provisions allowing termination where a party becomes insolvent. However, insolvency legislation has increasingly sought to restrict the operation of certain termination clauses in some circumstances, particularly where continued supply is considered important to a rescue or restructuring effort.

Businesses should therefore proceed cautiously before treating a contract as terminated. Acting too quickly may create additional risks and potentially expose a party to claims of its own.

Understanding what the contract says, and how insolvency law may affect those provisions, is often critical.

What happens to unpaid debts?

For many businesses, the immediate concern is recovering money owed by the insolvent company.

Unfortunately, insolvency often means there are insufficient assets available to satisfy all creditors in full. The likelihood of recovery can depend on several factors, including:

  • The insolvency procedure involved
  • The value of available assets
  • Whether security exists
  • The creditor’s legal status and priority
  • Potential claims against directors or third parties

Businesses will often need to determine whether they fall into the category of secured creditors, preferential creditors or unsecured creditors, as this can significantly affect recovery prospects.

In some cases, pursuing immediate litigation may not be the most effective course of action. Understanding the insolvency process itself may provide a clearer route to recovery.

What if goods or assets are involved?

Disputes frequently arise where goods, equipment or other assets have been supplied shortly before the insolvency event.

Questions commonly include:

  • Can supplied goods be reclaimed?
  • Who owns stock that has not yet been paid for?
  • What happens to goods held on-site?
  • Can equipment be recovered?
  • Are retention of title clauses enforceable?

The answers are often heavily fact-specific and can depend upon the contractual arrangements between the parties, how ownership was intended to pass and what has happened to the goods since delivery.

Where valuable assets are involved, swift action often proves a critical factor.

What should businesses do with ongoing projects?

Where insolvency affects a key supplier, contractor or project partner, immediate operational concerns frequently arise.

Organisations may need to consider:

  • Whether work can continue
  • Alternative suppliers or contractors
  • Rights to project documentation or intellectual property
  • Responsibility for delays
  • Cost overruns and mitigation measures
  • Insurance issues

These situations often give rise to disputes concerning contractual obligations, project milestones and responsibility for losses incurred following the insolvency. While legal rights will remain central, the commercial realities of maintaining business continuity often require careful balancing.

Are directors ever personally liable?

Although insolvency generally concerns the company rather than its directors, certain circumstances can give rise to personal liability risks.

Claims may arise where there are allegations of:

  • Wrongful trading
  • Fraudulent conduct
  • Breaches of directors’ duties
  • Transactions at an undervalue
  • Preferential treatment of creditors

Insolvency office-holders are frequently tasked with investigating the circumstances leading up to a company’s failure, and disputes can emerge long after the insolvency process itself has commenced.

For businesses considering recovery options, understanding whether claims against individuals may exist can sometimes be an important part in assessing the broader strategic picture.

Practical steps when a counterparty becomes insolvent

While every situation is different, organisations at the outset may wish to consider the following:

  • Identifying exactly which insolvency procedure has been commenced
  • Reviewing relevant contracts and termination provisions
  • Assessing outstanding debts and financial exposure
  • Establishing whether goods, assets or intellectual property are affected
  • Preserving key documentation and communications
  • Evaluating alternative supply arrangements
  • Obtaining legal advice before taking irreversible steps

Early action can often preserve options that may become significantly more difficult to pursue later.

Looking ahead

A counterparty’s insolvency can be disruptive, costly and uncertain. Understanding the legal and commercial landscape at an early stage however, offers businesses the ability to pursue more informed decisions, ultimately, allowing for them to better safeguard their position.

In circumstances where financial distress emerges, the most effective response is not always necessarily the fastest. Steps underpinned by a clear understanding of the legal options available – and the risks that lie ahead – are frequently the forge through which durable solutions are made. Whether the issue concerns unpaid debts, disrupted supply chains, asset recovery, contractual rights or potential claims against directors, a measured and strategic approach – more often than not – serves to define the contours which can most significantly shape the final outcome.

Key takeaways

  • Insolvency does not always mean a business immediately ceases trading
  • Understanding the insolvency process involved is critical
  • Contractual rights may be affected by insolvency legislation
  • Debt recovery options will depend on creditor status and available assets
  • Asset ownership and retention of title disputes commonly arise
  • Businesses should prioritise both legal protection and operational continuity
  • Early strategic action can preserve valuable options and improve outcomes

This insight is one of a series of Checkmate articles exploring the core themes that underpin modern commercial disputes, from post-acquisition claims to shareholder conflicts and directors’ duties.

To access the full guide and build a broader understanding of the risks and strategic considerations across these areas, visit here.

Checkmate – freezing injunctions

Corner of a chessboard

Checkmate – your essential guide to commercial disputes

This series of articles provides a valuable point of orientation to help readers navigate uncertainty with greater confidence.

Read our Checkmate series

Formal dispute resolution processes have a reputation (perhaps deservedly) for being lengthy and time consuming. This is especially true of litigation before courts and, to some extent, arbitration. If you are a claimant seeking to recover a sum of money, you may be faced with a wait of several years. That delay can be compensated for with interest. But what is a claimant to do when faced with a defendant who may take advantage of the delay to secrete assets away from the reach of the courts so that any victory is Pyrrhic?

The answer, very often, lies in the interim freezing order, which is an interim remedy available in English courts to support not only English litigation, but foreign litigation and even arbitration.

This article forms part of our Checkmate Series – your essential guide to commercial disputes, a collection of practical insights designed to help businesses navigate common dispute scenarios with clarity and confidence. Explore the full guide here.

What is a freezing injunction?

Modern interim freezing orders took their original name of Mareva injunctions from a Court of Appeal case in 1975 (Mareva Compania Naviera SA v International Bulk Carriers SA [1975] 2 Lloyd’s Rep. 509), although a similar order was first granted earlier that year. They were renamed as part of the civil procedure rules reforms in 1999, which sought to simplify court procedure including by replacing arcane legal names with plain English where possible.

They are an order against a person (the respondent) freezing some or all of that person’s assets. Disobeying the order is a contempt of court, and a freezing order will carry a stern warning (the “penal notice”) on the front of it warning of the consequences of disobedience. The order will remain in place until it is varied. The advantage is that the applicant for the freezing order knows that assets will be preserved to be recovered if the applicant is successful in its dispute with the respondent.

How do you get a freezing injunction?

It is common to apply for a freezing injunction without notice to the respondent (since otherwise the respondent might take steps to put their assets beyond reach upon hearing of the application).

The applications are often made on an urgent basis. They need to be supported by evidence, usually in the form of an affidavit (a witness statement sworn in front of an independent solicitor). 

To grant a freezing order, the respondent must usually establish the following:

  • the English court has jurisdiction
  • the applicant has a cause of action
  • the applicant has a good arguable case on the merits in relation to their cause of action
  • there must be a risk that assets of the respondent will be dissipated

The applicant will also usually be required to provide undertakings to the court to pay for damage caused to the respondent.

It is important to note that, because the applications are usually made without notice (and the respondent does not have the chance to put their case), there is a duty of full and frank disclosure to the court. This means that the applicant must tell the court of all facts relevant to the application, whether they are helpful to their application or not.

What should I do if I receive a freezing injunction?

If you should find yourself the object of a freezing injunction, you should seek legal advice immediately. You will need to prepare for a hearing (the “return date”) at which you will have the opportunity to put your case as to why the injunction should not have been granted. But you will also need to start complying with the injunction immediately. This means that you cannot deal with your assets. It is also common for you to have to disclose details of your assets to the court and to the applicant. Careful compliance is essential, and best done with legal advice.


This insight is one of a series of Checkmate articles exploring the core themes that underpin modern commercial disputes, from post-acquisition claims to shareholder conflicts and directors’ duties.

To access the full guide and build a broader understanding of the risks and strategic considerations across these areas, visit here.

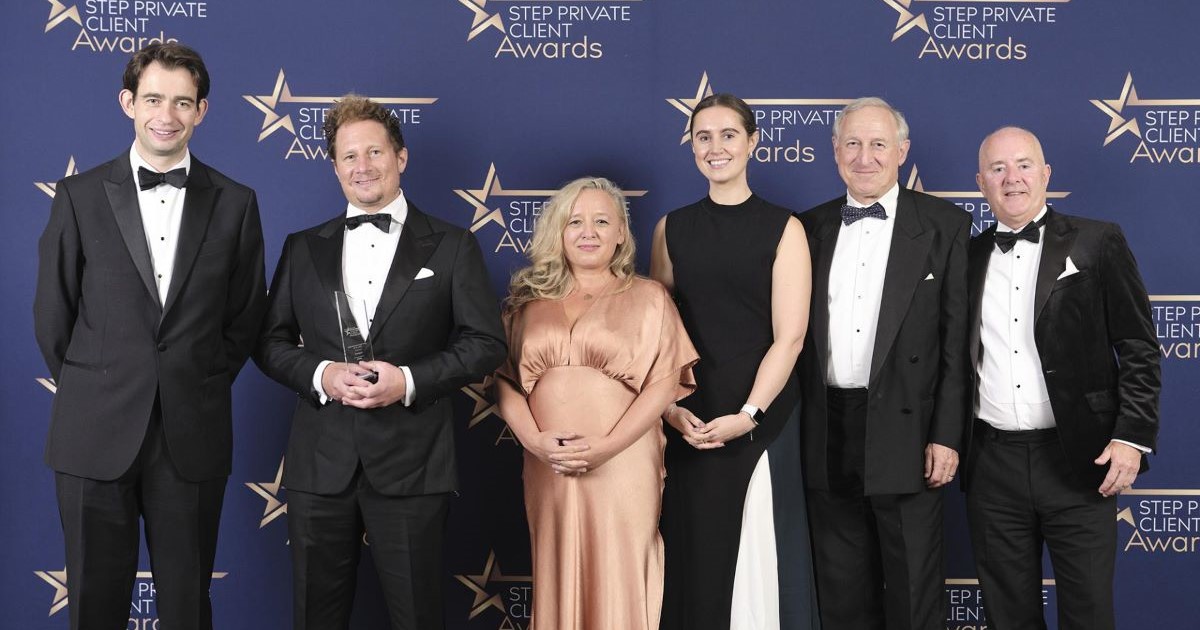
Forsters double award win at the STEP Private Client Awards 2026

Forsters picked up two awards at this year’s prestigious STEP Private Client Awards:

  • International Legal team of the year (large firm)
  • Digital Assets team of the year

In awarding Forsters International Legal team of the year, the judges highlighted how:

“Forsters combines legal advice with an appreciation of family dynamics, governance and conflict prevention. Its innovative approach and exceptional cross-border work made it a deserving winner.”

The judges also named Forsters as Digital Assets team of the year, noting that:

“Forsters is a leading voice on digital assets. The team demonstrated expertise across litigation, succession planning, tax and international structuring. Its commitment to education and collaboration helped make it a clear winner.”

The recognition follows Forsters’ launch of a base in Abu Dhabi Global Market, marking a significant milestone in the firm’s international growth. It also reflects the firm’s commitment to meeting the evolving needs of global private wealth clients, including advising on emerging asset classes.

The STEP Private Client Awards are recognised globally by firms and practitioners as a definitive benchmark for excellence, setting the industry gold standard and reinforcing best practice across the profession.

Forsters announces social mobility partnership with The Academy of Real Assets

We are delighted to announce a new partnership with the Academy of Real Assets, a social enterprise dedicated to introducing young people from under-represented backgrounds to careers in the real estate sector. The Academy works with schools and industry members to broaden access to opportunities across the real estate and real assets industry, helping thousands of students gain valuable insights, skills and connections that can support their future careers.

At Forsters, our ambition is to attract, retain and develop diverse talent at every level by reducing barriers to entry and progression within the legal profession. As one of London’s leading real estate law firms, we recognise both the opportunity and responsibility to use our expertise, networks and industry relationships to help young people access careers they may not otherwise have considered.

Through this partnership, we look forward to building on our existing outreach work with schools and collaborating with peers across the sector to inspire the next generation and broaden awareness of career opportunities within real estate.

Read more about our approach to diversity and inclusion here.

Employment Rights Act Watch: September 2026 edition

Welcome to this month’s edition of Employment Rights Act Watch, bringing you the very latest on the implementation process, together with practical tips on what you should be focusing on now to prepare for the changes ahead.

For an overview of the key changes under the Act and to access detailed guidance on topics most relevant to you, please browse our Employment Rights Act Hub.

Where are we on implementation?

One of the Starmer government’s last acts in office was to update the implementation timeline for the Employment Rights Act 2025. So far, the Burnham government has given no indication that it intends to depart from that timeline. On that basis, we are working toward the next significant milestone in October, with the following implementation dates:

New duties to review and consult on tips and gratuities policies are subject to consultation on a re-issued draft Code of Practice and are expected to be brought into effect by the end of the year.

The next major implementation milestone will be 1 January 2027, with changes to the unfair dismissal framework and to ‘fire and rehire’ anticipated to come into effect.

What should you be focusing on?

October readiness

The October implementation dates are now fast approaching and your main focus should be on ensuring that your organisation is ready for these changes. Note, in particular:

Tribunal time limits

The extension of Tribunal time limits from three to six months will take effect on 1 October (9 November in Scotland). There is nothing you need to do to prepare, but the change may affect the dynamics of early-stage employment disputes and it is important to ensure that team members dealing with contentious exits or settlement discussions are aware of it. Note that the extended time limit will apply in relation to causes of action arising on or after 1 October 2026 – claims presented (after 1 October) in respect of causes of action arising before that date will continue to be subject to the three-month time limit.

Changes to the harassment framework

With changes to the legal framework on harassment expected to come into force on 30 October 2026, you should now be completing programmes to review and enhance preventative measures relating to sexual harassment and to put in place measures to protect employees against broader harassment by third parties (including clients, customers and suppliers). Read more about the changes, what they mean for you and how you can prepare in our in-depth articles, “Raising the bar on sexual harassment prevention: The enhanced duty explained” and “When lines are crossed: Are you prepared for third-party harassment liability?“.

Changes to trade union law

The Act extensively reforms trade union laws. For the most part, these will impact organisations who already recognise a trade union or who operate in heavily unionised environments. If that applies to you, we recommend that you take specific advice on how the changes may affect you.

Two changes expected on 30 October potentially affect businesses outside traditionally unionised environments, and it is important that you are aware of them even if you do not generally deal with trade unions:

  1. New duty on all employers to inform workers of their right to join a trade union. After a consultation on the detail of this new duty closed in December, we are still awaiting the government’s confirmation as to what employers need to do to comply. You can read more about what we know, and the direction things are likely to take, here.
  2. New trade union access rights. You can read more about the access rights here. At a minimum, you should ensure that managers and HR professionals throughout your business are aware of these rights and that escalation routes for formal and informal approaches from a trade union are clear and effective. If you think your business is likely to receive an access request from a trade union, you may wish to take a more proactive approach and give thought to how appropriate access arrangements might be designed.

January readiness

You should not lose sight of the next implementation milestone on 1 January 2027 and the changes to the unfair dismissal framework. The changes are significant and will substantially increase risk around ordinary course dismissals. You should use this time to:

  • Ensure that hiring and probation procedures are robust.
  • Manage problem cases proactively, with the aim of concluding any exit conversations that need to be had before the new regime enters into force.
  • Review wider procedures around handling terminations, including your procedures for managing the expiry of fixed-term contracts.
  • Consider whether more bespoke risk mitigation strategies for key hires are necessary.

Read more about the changes, what they mean for you and how you can prepare here. You can also read more about managing fixed-term contracts in the brave new world of six-month qualifying periods and uncapped unfair dismissal claims here. If you would like to discuss your approach, or talk through more bespoke risk mitigation strategies, please contact a member of the team.

The longer view

The Employment Rights Act reforms are extensive and implementation will continue into 2027. We are awaiting further detail on many of these changes, so there is a limit to what you can meaningfully do to prepare.

One area where we do recommend you take action is on holiday pay. As of 6 April 2026, employers are under obligations to keep records relating (among other things) to holiday pay compliance, and the Fair Work Agency (FWA) will be given powers to enforce holiday pay compliance from 2027. This will increase risk for employers who do not calculate holiday pay correctly. There is a window of opportunity now to review your holiday pay arrangements and ensure you are compliant. You can read more the proposals, what they mean for you, and what you can do prepare here. If you require support carrying out an audit or if you would like to discuss the best approach to remedying any issues identified without generating disputes, please reach out to a member of the team.

What is the very latest on the Employment Rights Act?

The government has launched a consultation on a re-issued draft Code of Practice on Fair and Transparent Distribution of Tips. The draft is in substantially the same form as the version previously issued. The consultation will close on 29 September 2026 and we expect new rules on tipping (including a new duty to consult on tipping policies) to be brought into effect by the end of the year.

The government consultation on reforms affecting zero- and low-hours workers closed on 25 August. A new government impact assessment suggests the cost to business of these measures is likely to be between £350 million and £2.9 billion per year. You can read more about the controversial proposals here.

The government consultation on statutory holiday pay enforcement will close on 22 September 2026 – you can read more about this here. We expect the government response over the coming months.

Navigating the Employment Rights Act 2025

An overview of the key changes and some general guidance on steps you can sensibly take to prepare.

Explore now

Forsters recognised in the latest 2026 Spear’s Legal Indices

The latest 2026 Spear’s Legal Indices have just been published, and we’re pleased to share that Forsters lawyers have been included across the Corporate, Employment, Landed Estates and Litigation and Dispute Resolution listings:

Corporate

Landed Estates

Employment

Litigation and Dispute Resolution

These rankings follow the inclusion of Tracy Evlogidis in the Immigration index and James Brockhurst in the Cryptocurrency & Digital Assets listing earlier this year.

About the Spear’s 500

The Spear’s 500 is an annual, curated guide to leading private client advisers, lawyers and specialists serving high-net-worth and ultra-high-net-worth individuals, families and family offices.

It is designed to help identify trusted specialists with the expertise and experience to advise on complex and often highly sensitive legal, commercial and private client matters.

Rooftop solar: Unlocking a major opportunity for commercial real estate

Commercial real estate has a critical role to play in supporting the UK’s transition to a lower-carbon, more resilient energy system. Yet despite growing momentum and strong industry interest, rooftop solar remains significantly under deployed across the sector, with substantial untapped potential sitting on commercial buildings throughout the UK.

To better understand the opportunities and barriers facing the market, we have partnered with Real Estate:UK and Push Power to commission research undertaken by Cushman and Wakefield exploring the current state of rooftop solar deployment across UK commercial real estate. Drawing on a survey of 70 organisations representing more than £500 billion of real estate assets under management, industry roundtable discussions and supporting market analysis, the report examines adoption levels, commercial drivers, key challenges and the policy interventions needed to accelerate deployment at scale.

The findings show that while rooftop solar is increasingly viewed as a mainstream component of asset strategy and decarbonisation plans, deployment remains well below its technical potential. The report identifies a number of barriers, including leasing complexity, grid constraints, financing challenges and regulatory uncertainty, while also setting out practical recommendations to help unlock a rooftop solar revolution across the UK’s commercial building stock.

From Opportunity to Infrastructure: Scaling Rooftop Solar in Commercial Real Estate:

Supporting your sustainability journey

Working across all real estate sectors, including commercial, residential, rural, planning and construction, we bring together the expertise needed to embed sustainability into transactions, developments and asset management.

Explore now

Forsters has been named as a supplier on Government Commercial Agency’s (GCA) RM6374 Legal Panel for Public Sector framework under Lot 2: Focused Legal Support

Forsters has been named as a supplier on Government Commercial Agency’s (GCA) RM6374 Legal Panel for Public Sector framework under Lot 2: Focused Legal Support.

We’re delighted to have been appointed to this framework, creating opportunities to support a broader range of public sector organisations with the specialist advice they need, drawing on expertise from across the firm, including Real Estate Disputes, CRE, and Planning. The appointment enables public sector organisations to access our specialist legal advice and support through a compliant and efficient route to market. Through Lot 2, buyers can procure focused legal expertise across a range of practice areas to supplement in-house capability, respond to peaks in demand and access specialist advice when required.

Government Commercial Agency (GCA) is the UK’s central commercial and procurement organisation, connecting public and private sectors to achieve the best outcomes for the UK and its citizens. GCA uses its commercial expertise to create a simpler procurement experience that redirects valuable resources into essential public services – creating value for the nation.

Forsters supports over 100 Cloudflare employees affected by large-scale redundancy programme

Forsters’ Employment and Partnerships team has supported over 100 employees affected by a collective redundancy at Cloudflare, a global web infrastructure company.

The redundancies formed part of a wider workforce reduction programme involving around 1,100 employees worldwide, approximately 20% of Cloudflare’s global workforce. The announcement made headlines after the company’s leadership cited increased AI adoption as a significant factor behind the cuts.  Over the course of the project, we supported more than 120 Cloudflare employees in the UK.

This matter highlights our team’s extensive experience advising on departures and large-scale redundancy programmes in the fast-paced technology sector, helping affected employees navigate both the employment and equity-related issues that often arise in the industry.

Forsters’ team was led by Jo Keddie and Dan Parker.

When a workplace investigation starts: Why the first 48 hours matter

When a complex workplace issue lands on your desk, the pressure to act quickly can be immense. Whether it’s a grievance, a whistleblowing concern or allegations involving senior individuals, the instinct is often to jump straight into the detail.

But some of the most important decisions in a workplace investigation are made before the investigation properly begins.

In the first episode of Workwise: Navigating workplace investigations, Joe Beeston and Danielle Crawford are joined by our HR Director, Ann-Marie Comer, to discuss a scenario that will feel increasingly familiar to HR professionals and in-house lawyers: a lengthy grievance, apparently generated using AI, containing multiple allegations against a number of individuals.

While fictional, the scenario highlights several challenges employers are already facing in practice.

AI is changing the landscape

The growing use of AI is creating new challenges for HR teams and employers.

AI-generated grievances can quickly transform relatively focused concerns into lengthy documents containing multiple allegations, legal concepts and references that may not always be relevant or accurate. While AI can help individuals articulate concerns, it can also make it more difficult to identify the core issues that genuinely require investigation.

At the same time, employers are increasingly having to consider whether confidential, commercially sensitive or personal information has been entered into public AI tools and what risks this may create from a data protection and confidentiality perspective.

Unfortunately, there is no shortcut: evaluating a complaint begins with engaging with it in detail, even if if is long and core issues are difficult to follow. HR professionals will then want to try to work with complainants directly to understand what is really going on. AI may be changing how workplace concerns are raised, but it does not remove the need for careful judgement, clear communication and meaningful human interaction.

Understand what you’re investigating

One of the biggest challenges we see with the emergence of the AI grievance is scoping. What is the grievance actually about? What are the complainant’s core concerns? Engaging with the individual directly can be hugely valuable in understanding the scope of a complaint and, where necessary, narrowing it.

It will also shape how issues will be investigated. One of the biggest risks at the outset of a workplace investigation is assuming that every allegation belongs within the same process.

What arrives as a grievance may also contain whistleblowing concerns, regulatory issues, data protection risks or allegations that require a different approach altogether. Before deciding on next steps, employers should take the time to identify exactly what allegations are being made, understand which policies apply and consider whether multiple investigations may be required.

Getting the scope right at the beginning helps create a clear framework for the investigation (or investigations) and can prevent significant problems further down the line. It will also help HR professionals take a broad view and involve the right stakeholders to ensure that the response to a complaint is shaped not only around the HR considerations but also any potential wider implications for the business.

Communication matters more than you think

As workplace investigations become more complex and document-heavy, it is easy to focus solely on evidence gathering and process.

However, one of the strongest themes emerging from the discussion was the importance of communication. Employees who raise concerns want to know they are being heard, while individuals who are the subject of allegations need clarity about what happens next.

Engaging thoughtfully when a complaint first emerges can help set an investigation up for success. When investigations take time, regular updates can make a significant difference. Even a brief communication explaining why a process is taking longer than expected can help maintain trust and reduce frustration.

Ultimately, investigations involve people, not just policies and procedures.

A practical reminder for employers

There is no one-size-fits-all approach to workplace investigations. Every situation is different and requires careful consideration of the facts, the people involved and the potential risks.

Taking the time to understand the issues, establish the right scope, communicate effectively and identify any wider concerns can make a significant difference to the outcome of an investigation.

As workplace investigations continue to evolve, particularly with the growing influence of AI, getting the first 24-48 hours right has never been more important.

Listen to the full discussion

These are just some of the issues explored in episode 1 of Workwise: Navigating workplace investigations, where Joe Beeston, Danielle Crawford and Ann-Marie Comer discuss the practical realities of managing workplace investigations and the steps organisations can take to avoid common pitfalls from the outset.

Conducting credible workplace investigations

This practical guide for employers will give you the confidence to conduct a professional investigation that meets your legal and regulatory obligations.

Read our guide