Over the summer the Court of Appeal gave judgment on an appeal brought by the City of London, relating to a rates mitigation scheme. The decision will be of keen interest to any landlords trying to manage their liability for non-domestic rates, or business rates. The court found that a common existing scheme is not effective. The ruling aligns the court with the much stricter approach we are seeing tax authorities are taking. The case itself was The Mayor and Commonalty and Citizens of the City of London v 48th Street Holdings Ltd & Another [2026] EWCA Civ 970 (KB).
It goes without saying that any landlords who use these or similar schemes should speak to their legal advisors.
The scheme
The scheme in question is a common one:
A landlord has empty premises, and has used up the period of relief from paying business rates.
A third party rates mitigation business (the “tenant”) takes a lease of empty premises from the landlord.
The tenant moves some materials (in this case boxes) into the premises and occupies (via the boxes) for long enough that the landlord will be able to claim empty rates relief.
The tenant accepts liability for business rates during its period of occupation. As between the landlord and the tenant, the landlord invariably makes a payment to the tenant at least equal to the business rates payment.
When the tenant later vacates, the landlord is able to claim rates relief, and the tenant takes a success fee.
These schemes have been controversial for many years, with local authorities challenging them with varying degrees of success. However the High Court has previously found a similar scheme to be effective at resetting the landlord’s entitlement to business rates relief.
The ruling
In this case, the Court of Appeal overturned the previous ruling by the High Court that had upheld these types of schemes. It is relevant to this case that it was common ground that the occupation was only for the benefit of rates mitigation; it was relevant that there was nothing in the boxes that the tenant needed to store. The Court said if the only benefit for the tenant was to achieve rating relief, that did not count as occupation and would fall foul of other case law whereby the Court will not uphold a structure that has been created purely to reduce a party’s tax liability. That would run contrary to the intention of the legislation.
What now?
Landlords will want to assess any existing arrangements in light of the judgment.
As things stand, use of schemes such as the one considered by the Court will not allow a landlord to benefit from repeat empty rates relief. Given the ruling could constitute an existential threat to the rates mitigation business involved, a further appeal to the Supreme Court may be in the works. Watch this space.
Landlords who are looking to mitigate rates liability will still have other avenues open to them, such as lettings to pop-ups or other occupiers. Equally, given the emphasis placed on ‘what was in the boxes’, it may be that the case might have been decided differently if the boxes had contained something that needed to be stored – for example, archive material.
"something done for no purpose other
than the avoidance of liability for rates will be ineffective in achieving that purpose" - Lady Justice Falk
A price for holding power? Ofgem consults on a Data Centre Grid Commitment Fee of up to £712,500 per MW
Power has become the critical constraint for many data centre developments. Against a backdrop of increased public scrutiny, growing AI demand, increasing pressure on the electricity network and a crowded connections queue, Ofgem has launched a consultation on proposals designed to deter speculative projects and prioritise those that are genuinely capable of being delivered.
The headline proposal is a new Data Centre Commitment Fee, which could require developers of larger schemes to provide financial security of between £237,500 and £712,500 per MW of requested capacity to retain their position in the grid connections queue.
For a sector where access to power is often one of the most valuable project assets, the consultation could have significant implications for how schemes are structured, funded and brought forward.
Why is Ofgem proposing this?
Between November 2024 and June 2025, contracted demand in the electricity connections queue increased from 41GW to 125GW. Ofgem estimates that around 73GW of this relates to data centre projects. To put that into context, peak electricity demand across Great Britain in 2025 was around 45GW.
Ofgem’s concern is that the current system makes it relatively inexpensive to secure and retain a queue position. As a result, speculative or non-viable projects may be taking up valuable network capacity, distorting network planning and delaying projects that are genuinely capable of connecting.
The consultation forms part of the wider Curate, Plan and Connect programme being developed by Ofgem, NESO and Government to improve the operation of the demand connections system.
What is the proposed Data Centre Commitment Fee?
Ofgem is proposing that certain data centre projects should provide financial security linked to the capacity they are seeking to connect.
The proposed fee is between 2.5% and 7.5% of average data centre capital expenditure, which Ofgem estimates equates to approximately £237,500 to £712,500 per MW of requested capacity. Ofgem’s calculation is based on estimated average capital expenditure of £9.5 million per MW.
Importantly, this is not proposed as a simple upfront charge.
Instead, developers would be required to secure 100% of the potential fee from the point at which a Gate 2 connection offer is accepted through to energisation. The security would be returned if the project progresses as planned and reaches energisation. However, the fee could become payable if the project terminates, reduces its contracted capacity or otherwise fails to comply with the applicable requirements.
The proposed structure is intended to ensure that developers holding scarce grid capacity have a credible route to delivery and a sufficient financial commitment to progress their projects.
What sort of sums are we talking about?
The potential financial exposure is significant.
Based on the consultation figures:
A 50MW project could require financial security of between £11.875 million and £35.625 million.
A 100MW project could require financial security of between £23.75 million and £71.25 million.
A 250MW project could require financial security of between £59.375 million and £178.125 million.
These are illustrative calculations based on Ofgem’s proposed range rather than confirmed charges, but they demonstrate the scale of the financial commitment that developers may be expected to make to retain their position in the grid connections queue.
Which projects would be affected?
The consultation proposes that the commitment fee should apply to data centre projects with a capacity of 40MW or more that:
connect directly to the transmission system; or
connect to the distribution network and are subject to a Transmission Entry Assessment (essentially a process used where a project is connecting to the distribution network but is large enough to have an impact on the wider transmission system) or equivalent process.
The proposals are intended to apply to both existing and future projects, although Ofgem is consulting on exemptions and transitional arrangements. These include an exemption for projects due to energise within a period of six months of the fee being introduced, together with grace periods for certain existing connection agreements and offers.
The proposed 40MW threshold and the level of the fee remain open for consultation. They should not be treated as settled policy.
More than just a fee
The consultation is not solely about financial commitments.
Alongside the commitment fee, Ofgem is proposing new data centre queue management milestones aimed at ensuring projects are making genuine progress towards delivery.
Developers may be required to demonstrate matters such as:
a credible compute customer or end user;
procurement of long-lead electrical equipment;
financial capability; and
technical readiness.
Separate pathways are proposed for self-operated facilities and projects intended for lease or sale, reflecting the different ways in which data centres are developed and brought to market. Projects that fail to meet the requirements could lose their queue position.
What does this mean for developers?
The consultation reflects a broader shift in the market.
Historically, obtaining a grid position was often viewed as a key milestone in making a project viable. Going forward, developers may need to demonstrate much more than site control and planning potential. Power strategy, funding arrangements, procurement planning and end-user demand could increasingly come under scrutiny before a project is permitted to retain valuable grid capacity.
For developers, funders and landowners involved in the data centre sector, the proposals are therefore about far more than connection mechanics. They raise fundamental questions about project deliverability, funding structures and the value of powered land.
At a time when AI Growth Zones, digital infrastructure and data sovereignty remain high on the Government’s agenda, access to power continues to be one of the defining issues for the UK data centre market.
The concept works, but does the proposed structure?
I have spoken to contacts across the data centre sector who broadly agree with Ofgem’s underlying objective.
There is a legitimate need to address speculative applications and ensure that grid capacity is reserved for projects with a genuine prospect of being delivered. In principle, a meaningful financial commitment could improve the health of the queue and help credible developments secure access to power more quickly.
The concern is that the proposed structure may not always distinguish between a speculative project and a feasible development that simply needs time to come together.
Data centre developments are complex. Land rights, planning, funding, customer demand, procurement and power arrangements do not necessarily fall into place at the same time. A project can be credible and commercially viable without having every element tied down when its connection offer is accepted.
Requiring a developer to lock up tens of millions of pounds from offer acceptance until energisation could therefore price out, or materially delay, projects that have a realistic route to delivery. It could also place particular pressure on developers bringing forward powered land before an operator, funder or end user has been secured.
Should the security be released in stages?
One possible answer would be to align the financial commitment more closely with the proposed queue management milestones.
If Ofgem is going to require developers to demonstrate that their projects have reached particular stages, there is a strong argument that a percentage of the original security should be released as those stages are achieved.
The precise triggers and release percentages would need careful consideration. The principle, however, is relatively straightforward. A developer that has provided clear evidence of continuing project maturity presents less of a speculative risk than it did at the point of offer acceptance.
A staged release would retain a meaningful financial incentive to progress the project, while reducing the burden of locking up potentially tens of millions of pounds throughout the entire connection period.
It may also create a better alignment between the two limbs of Ofgem’s proposal. If the milestones are intended to provide continuing evidence of deliverability, the level of security could reduce as that evidence becomes stronger.
This could strike a more proportionate balance between clearing speculative capacity from the queue and allowing credible developments the time and financial flexibility they need to reach energisation.
Ofgem will no doubt be concerned that any release mechanism could be open to manipulation and reduce the deterrent effect of the policy. There may be a middle ground, however, between releasing no security until energisation and returning all security only at the end of the project lifecycle.
Key dates
29 July 2026: Ofgem published the consultation.
16 September 2026: The consultation closes.
Later in 2026: Ofgem intends to take decisions on the proposals after considering consultation responses. No fixed implementation date has been published.
What should developers be doing now?
Developers should use the consultation period to consider how the proposals would affect both individual schemes and their wider development pipelines.
In particular, they should consider:
whether the proposed 40MW threshold is the right trigger for the commitment fee;
whether the proposed £237,500 to £712,500 per MW range is proportionate;
how the security requirement could affect funding, investment and land promotion structures;
whether the proposed milestones reflect how data centre projects are brought forward in practice;
whether a staged release of security would provide a fairer balance between deterrence and deliverability;
whether the proposed exemptions and transitional arrangements adequately protect existing projects; and
how the proposals could affect the value and marketability of powered land.
Developers should also model the potential exposure across their existing pipelines. A 100MW project could require security of between £23.75 million and £71.25 million, which may materially influence project economics, funding strategies and transaction structures.
That analysis should then inform the evidence submitted to Ofgem. Worked examples showing how the fee would affect viable schemes, funding costs and delivery timetables are likely to be more useful than a general objection to the principle of reform.
Those active in the sector should review the proposals carefully, stress-test the impact on their development pipelines and engage with Ofgem before the consultation closes on 16 September 2026. The concept may work, but the detail will determine whether the reforms remove speculative capacity without also shutting out feasible projects that need time to mature.
This is the industry’s opportunity to help shape a framework that removes speculative projects from the queue without discouraging the very developments the UK is seeking to attract.
Disclaimer
The proposals discussed in this article remain under consultation and may change before implementation. The potential impact will vary depending on the nature, scale and connection arrangements of each project. Specific legal, regulatory and commercial advice should be sought in relation to individual circumstances.
Forsters has advised BlueFive Private Wealth on the sale of SYSTEMS, a landmark office building in Brook Green, West London, to JD.com, a leading supply chain-based technology and service provider. The c.127,000 sq ft building will become JD.com’s UK headquarters.
SYSTEMS is one of West London’s most distinctive office buildings, with a history spanning almost a century. Originally constructed in the 1930s, the building is known as the birthplace of the world’s first business computer, from where it derives its modern name.
Forsters has been involved throughout the asset’s transformation. Our specialist Construction team advised on the extension and redevelopment of the building, including a two-storey extension to the top of the building and a three-storey extension to the rear.
The recent redevelopment was led by General Projects and designed by Buckley Gray Yeoman. The project preserves the building’s architectural heritage while transforming it into a workplace destination focused on sustainability, technology and occupant wellbeing. The redevelopment increased the building’s net internal area by almost 50% and delivered a range of occupier amenities, including communal terraces, cycle facilities, showers and locker rooms, with the building designed to achieve BREEAM Excellent and EPC A ratings.
An interesting and logical extension to this trend is the intergenerational model for care homes and later-living developments. In March, a report from the All-Party Parliamentary Group for Housing and Care for Older People recommended that we “recognise intergenerational communities as essential social infrastructure that fosters inclusive and reciprocal relationships and everyday mutual support between people of all ages and backgrounds”.
For those unfamiliar with the concept, such schemes bring together older residents and younger people, whether students, young families or working-age households, in shared or adjacent living environments. The benefits can be manifold, from fostering meaningful social contact and reducing isolation to creating more vibrant, mutually supportive communities and boosting housing delivery.
Intergenerational housing schemes thrive in exactly the kinds of central, connected locations your article discusses. Proximity to universities, schools, workplaces, cultural institutions and younger populations is crucial.
The concept remains on the periphery in the UK, but there are encouraging signs of movement. A planning application was recently submitted for 85 intergenerational, zero-carbon-in-use homes at Ordnance Lane in York, with 40% affordable provision and a community-led development process.
In London, Melfield Gardens has been described as the UK’s first fully affordable intergenerational housing scheme, designed to tackle both loneliness and housing shortage.
And the design of Farmstead Road in Lewisham references intergenerational living, with mixed household typologies, flexible layouts and shared spaces.
In the US, a growing number of operators and universities are partnering to create retirement communities embedded within or adjacent to campuses. The model has real potential for the UK, given our concentration of civic universities.
The case for intergenerational housing in the UK is strong, with an ageing demographic, a housing crisis affecting multiple generations and a growing appetite for models that do more than simply provide beds.
This article was originally published by Property Week.
A “MEES-ed” opportunity? New EPC deadlines explained
Five years on, without any warning, on a nondescript Thursday and amidst political upheaval, we had a significant regulatory update.
For years, the industry has been working to an anticipated deadline of EPC B by 2030, EPC C by 2027 – but without any law to that effect. As the clock has ticked down, there was widespread thinking that dates would go back – but when? We now have the answer*, with this “interim response”:
No EPC C 2027 deadline
EPC B by 2031
1,000 sq m “buildings” only
I have had the pleasure of speaking with Green Street News and Property Week — links to the articles below (£). Without doubt the government has “kicked the can down the road” on smaller stock, but perhaps that is understandable, and progress is better than nothing, for an industry craving regulatory certainty…
*This is the “intention”, not law. We need legislation. With a new incoming PM, will this be a legislative priority? Could we see an about turn?
In my view, the government is kicking the can down the road where, arguably, the closest attention is required – the small poorest performing buildings
I attended the Gen+1 Elevate conference last week as part of the Forsters data centre team.
Demand for data centres is accelerating. That is no longer up for debate.
The more interesting question, and the clear theme from the panels, is whether projects can actually be delivered.
Across the panels, five themes stood out.
1. The real investment story is about execution, not yield
The numbers still work. Yields of 8-9%, and 5-7 year investment horizons continue to attract capital.
Investor focus, however, has clearly shifted.
The key question is no longer “should we invest?” but “can this scheme actually be built?”
That is driving a much sharper focus on:
planning risk;
power availability and timing; and
delivery capability and access to labour.
The rise of joint ventures reflects this. Investors are increasingly looking to partner with operators, energy providers and developers to access expertise they do not have in-house.
Collaboration though brings complexity. Alignment of interests, exclusivity and the risk of partners becoming future competitors are now live issues that need to be addressed early.
2. The definition of a “good site” is changing rapidly
Five years ago, a data centre site had a relatively clear profile. That is no longer the case.
Constraints around power, land and scale are forcing developers to rethink location and design. Sites that would previously have fallen outside the investable universe are now being revisited.
Flexibility is becoming the defining characteristic.
There was also a degree of realism in the room. Certain trends, particularly around modular solutions and aspects of the AI ecosystem, were openly described as over-hyped. The expectation is that the market will consolidate, with a limited number of long-term winners.
3. Power is no longer a constraint. It is the constraint
Every conversation ultimately came back to power.
The gap between demand and available capacity is now well understood. What is less well understood is the complexity behind it.
As we are seeing on our projects, “having power” is not a binary issue. It raises a series of more difficult questions:
when will it be available;
how reliable is it; and
what infrastructure is required to support it.
Operators are responding in different ways. Some are exploring on-site, behind the meter, generation and alternative energy solutions. Others are seeking greater control of their supply chain to reduce reliance on constrained infrastructure.
The conclusion is clear. Power availability, in both timing and structure, is now the single biggest factor in determining whether a project proceeds.
4. The delivery model is under strain
Even where land and power are secured, delivery is far from straightforward.
Supply chains are stretched, with long lead times for key components, including fibre. At the same time, there is a growing disconnect between leasing expectations and construction timelines.
The industry is also facing a significant skills gap. Quite simply, there are not enough people to build what is currently in the pipeline.
In response, operators are:
bringing parts of the supply chain in-house;
increasing use of prefabrication; and
using AI to improve productivity and safety.
These are mitigation strategies rather than solutions. Delivery risk remains a core issue.
5. Planning and perception are becoming commercial issues
Planning is no longer just a legal or regulatory hurdle. It is a commercial one.
There is increasing scrutiny of how data centres are perceived at the development stage, particularly in relation to energy use and pressure on infrastructure.
At the same time, the industry is not always effective at communicating the value data centres generate. The economic impact of large-scale schemes is significant, but often poorly understood outside the sector.
This is creating a need for better engagement, clearer messaging and a more coordinated approach to how the industry presents itself.
What this means for clients
The takeaway is clear. Demand is not the problem. Delivery is.
For investors, developers and operators, that shifts the focus to execution from the outset. In practical terms, that means:
Front-loading strategy so that planning risk, power timelines and deliverability are assessed early;
Structuring partnerships carefully, with clear alignment on roles, risk and long-term strategy;
Taking a holistic view of viability, recognising that land, planning, power and infrastructure need to be considered together;
Actively managing delivery risk, particularly in relation to supply chain, skills and program assumptions;
Retaining flexibility, both in site strategy and structuring, as requirements continue to evolve.
The projects that succeed will not necessarily be those with the best sites or the strongest demand. They will be the schemes where planning, power, capital and capability are aligned from day one.
That alignment is now where the real value sits.
If any of these themes resonate, get in touch with Forsters’ data centre team. We are already advising on these challenges across a range of projects and bring the depth of experience needed to deliver them successfully.
Demand is not the issue. Delivery is. Five practical takeaways from Gen+1 Elevate on what is really driving the data centre market.
Timing is everything for possession on the basis of redevelopment
Pridewell Properties (London) Limited v Spirit Pub Company (Managed) Limited
The High Court handed down a decision which clarifies what a landlord must prove in order to satisfy its intention to redevelop under ground (f) of s.30(1) of the Landlord and Tenant Act (“1954 Act”), especially in relation to the timing of the redevelopment.
Background
In 2025 Spirit Pub Company (Managed) Limited successfully prevented its landlord (Pridewell Properties (London) Limited) from using ground (f) of the 1954 Act (“ground (f)“) to terminate its lease on the basis of redevelopment works.
The High Court (on appeal) has upheld part of the County Court’s decision and maintained that the landlord is prevented from obtaining possession. However, of most interest is how the High Court’s judgment dealt with the timing of the works and whether the landlord was in a position to commence works “on the determination of the current tenancy” in order to satisfy the ground (f) test.
Original decision
The County Court judge was satisfied that the proposed works were substantial enough to use ground (f). However, the landlord failed to evidence that it had a real prospect of obtaining the necessary funding for the development. The landlord’s proposed lender had indicated it would require directors/shareholders to provide guarantees. No evidence was provided to the court of the personal finances of those parties to enable the court to conclude that satisfactory guarantees would be provided.
There were a number of other hurdles the landlord needed to overcome in order to carry out a redevelopment, but the court concluded the landlord had a real prospect of dealing with them.
Unusually, the landlord had not applied for planning permission by the point of trial. The landlord needed to obtain access to the property to carry out certain surveys before submitting a planning application but did not have sufficient rights in the lease to obtain access. The court originally found that the landlord had a real prospect of overcoming the other issues it was facing and, other than the issue of funding, would be in a position to carry out the works “on the determination of the current tenancy” (which is the statutory test set out in ground (f)). That is despite not being in a position to commence works until 10–14 months after obtaining possession because it would take that long to obtain planning permission. The judge concluded that was within a reasonable time of the lease terminating, given circumstances where the landlord could not obtain access for surveys any earlier.
Appeal
Both parties appealed the judge’s decision.
Funding
The landlord’s appeal failed. The High Court concluded that the lender had indicated it would require security, and given that no evidence was provided that a satisfactory guarantee would be provided, the landlord could not show a real prospect of obtaining the necessary funding for the development. The landlord could not therefore show it had the necessary intention required under the 1954 Act to obtain possession on ground (f).
While the landlord’s appeal failed, the appeal judge went on to consider the tenant’s grounds of appeal (essentially challenging the original judge’s findings that the landlord had a real prospect of overcoming the other outstanding issues and that it would commence the works on determination of the lease).
Timing of the development
Of most interest is the judge’s decision regarding the timing of the redevelopment. The judge overturned the County Court’s decision and clarified that the relevant question is whether, given a delay in starting the works, a landlord could be said to intend to carry out the works on the termination of the lease, i.e. by a reasonable time after termination of the lease, not at any long-delayed time. What is a reasonable time/not any long-delayed time is not assessed on whether the delay is reasonable in the circumstances (here, the issue of obtaining access for surveys before applying for planning permission). The court will need to assess on a case-by-case basis what period of time could be added onto the date on which the landlord obtains possession without the works ceasing to be classified as being carried out on the termination date. That will vary depending on the nature of the development, for instance large sites are likely to take longer to mobilise contractors and carry out other preliminary steps.
Key outcomes
Those acquiring or assembling development sites need to ensure sufficient access rights. The landlord in this case was hampered as it was unable to access the property. This meant it could not obtain surveys or make a planning application and, therefore, could not show it would commence works on the determination of the lease. If a landlord is facing this issue, it may need to consider following an unopposed lease renewal process with a view to obtaining a redevelopment break in the new lease, with sufficient access rights for the landlord in order to pave the way for future redevelopment.
A lease terminates 3 months and 21 days after the conclusion of a court process. If a landlord needs a relatively short period after that before commencing works, it will still meet the ground (f) test. What is a short period will depend on the specific development, but is likely to include the time needed to secure and clear the property and mobilise contractors and take preliminary steps. Those carrying out large developments in urban areas are likely to be afforded longer than small developments at easily accessed sites.
For multi-let development sites it is important to plan ahead and ensure that the landlord can obtain possession of the other areas of the development site, at very similar times.
A landlord needs to take great care to flesh out the evidence behind its intention to redevelop, and ensure that it clearly shows how any unresolved issues will be dealt with.
“Thousands of London offices “risk obsolescence””…
“Landlords will struggle in the new regulatory environment given the “huge scope” of the challenges ahead”…
“A two tier office market”…
This article in Bloomberg is a reminder that despite the stark warnings, we don’t have any “new” energy efficiency rules for commercial buildings. There is no EPC B or EPC C requirement, despite the initial 2021 consultation proposals. We don’t know when DESNZ may make a decision, nor what that might be. As of February this year, according to DESNZ: “We are reviewing the consultation responses, making sure they are fair and proportionate and will update in due course” (see here). Five years on I don’t sense any urgency or conviction…and this is all in a legislative environment, where if the Government opts to act, it can move very quickly (e.g building safety, renter rights, ban on upwards only rent reviews). Clearly, priorities are elsewhere…
So are all these warnings misplaced? Will we ever see more use of the legislative “carrot” on energy efficiency? My prediction – we will not have any “new” rules in the near term (rumour has it that the Treasury fears the economic impact and will not bless anything). I suspect we will be in the same place in 5 years’ time.
That is not to say there is no polarised market, driven in part by the energy efficiency of buildings. There is no doubt that the quote below is, in part. true. However it is occupiers that are voting with their feet. I don’t think it is a question of “compliant/non-compliant” stock.
As demand increasingly concentrates on high-performing, energy-efficient buildings, the market is becoming more polarised,” it said. “Assets with strong sustainability credentials are commanding premium rents and values, while older, non-compliant stock are generating significantly lower rents and seeing longer void periods"
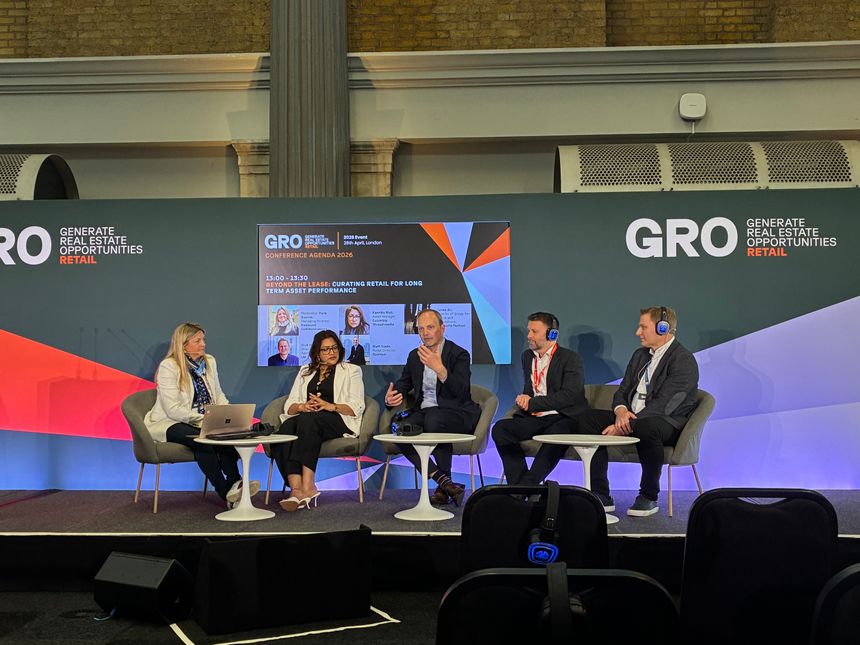
It was great to see so many familiar faces at the GRO spring event last week.
I also managed to attend a couple of interesting panel sessions and the overwhelming theme was that there has been a fundamental shift in what success looks like for physical retail and shopping centres.
Physical stores are no longer just a space to sell products. They are a data channel, a place to showcase, a place to create experiences and draw attention and a place to foster brand loyalty. Whilst a material amount of actual purchases may take place online, physical stores are still an important part of the retail business model.
We have seen a rise in pop-up stores, where smaller businesses can test their readiness for physical retail and gather data. A physical space allows these businesses to create a closer connection with their customers, obtain real-time feedback on their products and generate hype.
Combined with the diversification of offerings (think gyms, health centres and leisure), shopping centres are becoming community hubs and driving footfall. There is a more scientific approach to matching services with community needs as well as mixing long-standing, reliable brands with new and exciting concepts.
For many years the turnover rent lease has prevailed. However, I have to wonder if the measure of success of a physical store moves towards promotion rather than sales, we may see a re-imagining of the rack rent lease model to reflect the ever-changing partnership between landlords and occupiers.
Many of us will have read headlines in the press this week about the launch of the updated Future Homes Standard, which mandates zero carbon technology (e.g. solar panels, heat pumps) on most new domestic homes.
This is an important step and has been well received but this week has also seen, after a long wait and with somewhat less fanfare, the announcement of the Future Buildings Standard (FBS) for non-domestic buildings.
What is it and how did we get here?
As mentioned in the Solar Roadmap the Government has identified the key contribution that rooftop solar on non-domestic buildings can make in the road to net-zero. The Roadmap also envisages that the Building Regs regime will be the most reliable route for scaling up rooftop solar (as with domestic buildings and the ‘Future Homes Standard’).
In short, the FBS introduces mandatory solar PV (amongst other energy performance requirements) for new buildings via Part L of the Building Regulations in England.
What does this mean for commercial real estate?
New non-domestic buildings in England will be required to produce significantly lower carbon emissions than under existing regulations, specifically:
Non-domestic buildings (e.g. offices, warehouses, retail buildings) must incorporate solar panels equivalent to 40% of the building’s foundational area.
Other points to note:
Transitional arrangements apply to existing projects where an initial notice or application for building control approval has been submitted before 24 March 2027 (as long as that work starts before 24 March 2028).
The updated Regulations will apply to ‘higher-risk buildings’ (using the Building Safety Act definition) from 24 September 2027 (rather than the 24 March 2027) and different transitional provisions apply depending on whether a valid Gateway 2 application has been made before this date. Additionally, HRBs are exempt from the solar PV requirement.
Buildings containing accommodation which is not ‘self-contained’ (e.g. hotel rooms and student accommodation which do not have their own entrance, kitchen, bedroom, living space) will be assessed in line with the regulations for non-domestic buildings rather than domestic.
These requirements do not apply to:
Listed buildings or buildings in a conservation area if compliance would unacceptable alter the building’s character or appearance.
Buildings used primarily or solely as places of worship,
Temporary or modular/portable buildings (planned to be used for two years or less).
Industrial/workshop/agricultural buildings with no or limited energy demand for heating or cooling systems.
New and existing non-domestic buildings with less than 50 square meters of useful floorspace.
Carports and covered yards below certain sizes.
Key dates:
24 March 2027 – commencement of the FBS for most non-domestic buildings excluding higher risk buildings (HRBs).
24 September 2027 – commencement of the FBS for HRBs.
24 March 2028 – end of transitional arrangements for non-HRBs.
Final thoughts:
We welcome the Government publishing their response on the Future Buildings Standard and the continued recognition that rooftop solar on non-domestic buildings has a big part to play in reducing our reliance on gas and oil – particularly in light of recent events in the Middle East.
Nevertheless, a variety of challenges remain for landlords and developers looking to implement rooftop solar projects into their portfolios, including Grid connections, tenant engagement, concerns around rooftop structures but also viability/financing concerns. The withdrawal of VAT rebates on Chinese exported PV panels from 1 April 2026 is going to add significant costs to the cost of new PV panels.
The Future Buildings Standard is, therefore, a good start but is just one piece of a rather complicated puzzle. Click here to visit our commercial real estate page.
Recent attacks on data centres during the ongoing conflict involving Iran underline a stark reality. Data centres are no longer just commercial assets. They are strategic infrastructure.
Their targeting reflects how deeply digital infrastructure is embedded in modern economies. Banking systems, healthcare, logistics, government services and AI platforms all rely on uninterrupted access to data. When data centres fail, the consequences are immediate, wide‑ranging and often legally complex.
For businesses, developers and investors, this marks a shift. Operational resilience, data sovereignty and energy security are now legal and strategic considerations, not simply technical ones.
Resilience is becoming a legal obligation
Historically, resilience was addressed through service levels and technical design. That position is changing rapidly.
In the UK, data centres have been designated Critical National Infrastructure, and forthcoming reforms to the cyber and resilience regime will bring large data centres directly within the scope of regulatory oversight. Operators will be expected to demonstrate appropriate and proportionate measures to manage physical, cyber and operational risk, alongside mandatory incident reporting.
From a legal perspective, this raises key questions:
How resilience obligations are allocated between landowners, developers, operators and occupiers.
Whether existing leases, options, development agreements and collateral warranties adequately address business continuity, outages and force majeure.
The extent to which resilience commitments should be reflected in planning conditions, infrastructure agreements and funding documentation.
Standards such as ISO 22301 (Business Continuity) and ISO/IEC 27001 (Information Security) are increasingly relevant as reference points when assessing whether resilience measures are reasonable or market standard. This is particularly so in disputes, regulatory scrutiny or transactional due diligence.
Data sovereignty moves from policy to property
The conflict also sharpens the focus on where data is stored and under whose control.
Data sovereignty is no longer driven solely by data protection law. Geopolitical risk, sanctions exposure and national security considerations are influencing decisions about site selection, ownership structures and operational control of data centres.
For the UK and EU, this is accelerating demand for:
In‑country and sovereign data centre capacity.
Greater scrutiny of foreign ownership and control.
Contractual restrictions on data location, access rights and cross‑border failover arrangements.
From a property and development perspective, this has implications for planning strategy, investment structuring, joint ventures and long‑term asset value, particularly where sites are intended to support public‑sector, regulated or sensitive workloads.
Energy security becomes part of resilience
Recent events in the Middle East underline a further and often under‑appreciated risk. Data centre resilience is inseparable from energy security.
The current conflict involving Iran has driven a sharp increase in global oil prices, compounded by Qatar’s unprecedented decision to halt oil production. That development alone has exposed the fragility of global energy supply chains and the speed at which geopolitical events can translate into economic and operational instability. For infrastructure reliant on continuous, high‑volume power, the implications are immediate.
In this context, energy strategy is no longer just a question of cost or sustainability. Secure, controllable access to power is now a core resilience issue.
While the sustainability case for renewables is well established, the energy security case cannot be undervalued. On‑site and locally generated power, including wind, solar and tidal energy, can reduce dependence on volatile international markets and exposed fuel supply routes when paired with appropriate storage and grid balancing. Small Modular Reactors (SMRs) are also increasingly being examined as a potential long‑term solution for delivering stable, low‑carbon baseload power to energy‑intensive infrastructure such as data centres.
For developers, investors and occupiers, this reframes energy procurement as a legal and strategic risk issue. It raises questions around long‑term power availability, exposure to fuel and pricing shocks, planning and consenting strategy, and how energy risk is allocated contractually across ownership and operational structures.
In short, resilience is no longer just about surviving outages. It is about insulating critical infrastructure from geopolitical energy shocks. Sustainability remains vital, but the current conflict demonstrates that energy security now sits alongside decarbonisation as a primary driver of data centre strategy.
Resilience, sustainability and regulation are converging
Resilience cannot be separated from sustainability. For example, the EU’s Energy Efficiency Directive now imposes reporting and performance obligations on larger data centres, including energy usage, cooling efficiency and waste heat reuse.
While driven by climate policy, these requirements also support resilience by reducing strain on power, cooling and grid infrastructure. All of these are critical during periods of disruption. For developers, energy strategy is increasingly inseparable from resilience strategy.
What this means in practice
For those involved in developing, owning or operating data centres, the lesson is clear. Resilience, data sovereignty and energy security must be embedded at a legal and structural level, not retrofitted later.
That means:
Addressing resilience and power security at the site selection and planning stage.
Clearly allocating operational and energy‑related risk in contracts and funding documentation.
Treating regulatory compliance as a value‑preserving exercise, not a tick‑box.
The events in Iran may be extreme, but the signal is unmistakable. Data centres are now nationally significant assets. Their regulation, design and energy strategy are evolving accordingly.
Those who anticipate this shift will be better placed to manage risk, protect asset value and maintain trust in an increasingly uncertain world.
Cloud infrastructure was always theoretically vulnerable to kinetic warfare, but nobody had priced that risk in so far. Now that has to change
Today marks a major milestone for heat networks across Great Britain. From 27 January 2026, Ofgem officially begins regulating heat networks, creating a new compliance landscape for anyone who owns or operates a communal or district heating system. This change introduces long awaited consumer protections and brings heat networks closer to the standards seen in gas and electricity markets.
Why this matters
The Heat Networks (Market Framework) (Great Britain) Regulations 2025 take effect today and establish the legal foundation for the new regulatory framework.
The new regime is underpinned by Ofgem’s role as the statutory regulator for heat networks. Ofgem has published formal guidance, the regulatory timeline, registration requirements and consultation responses on its official heat networks hub here: Ofgem Heat Networks Regulation Hub.
Together these form the basis for a sector-wide shift in expectations relating to consumer protection, billing transparency and operational standards.
What owners and operators must do immediately
1. Confirm your regulatory role Heat network ownership brings responsibilities that fall into two regulated categories. The operator controls the physical system. The supplier provides heat to customers. Many building owners fall into both categories and must meet both sets of regulatory requirements.
2. Begin complying with Ofgem requirements From today, operators and suppliers must meet new consumer protection standards aligned with wider energy markets. These include transparent billing, clear communication, robust complaints handling and protections for vulnerable households. Consumers now also have formal access to the Energy Ombudsman for unresolved complaints.
3. Prepare for authorisation and registration All heat networks operating before January 2027 will be automatically authorised – ‘deemed authorisation’. Full registration with Ofgem must be completed by 26 January 2027. Operators of heat networks with deemed authorisation must register with Ofgem using the heat networks digital service by 26 January 2027. After this period, authorisation will be granted by application to Ofgem.
4. Carry out technical due diligence Alongside the new regulatory framework taking effect today, the Government is also developing the Heat Network Technical Assurance Scheme (HNTAS), which will introduce mandatory technical standards for both new and existing heat networks. According to the Department for Energy Security & Net Zero, HNTAS will not begin immediately but will be phased in with a planned launch in 2027, following further consultation and finalisation of the technical requirements. This phased approach is intended to give the sector sufficient time to understand, shape and prepare for compliance with the forthcoming technical standards.
5. Continue meeting metering and billing duties The introduction of Ofgem regulation does not replace existing obligations under the Heat Network (Metering and Billing) Regulations 2014. These duties include installing meters where feasible, billing based on actual consumption and maintaining accurate data records.
Looking ahead
With Ofgem now holding enforcement powers including financial penalties, compensation orders and ongoing audits, compliance is no longer optional. Today represents a major turning point for the heat network sector. Owners and operators who act early will be best positioned to reduce regulatory risk and deliver a more transparent and reliable service to consumers.
This shift marks an important step forward in building a fairer, more consistent and more resilient heat network market. It strengthens protections for consumers, raises operational standards across the industry, and supports the UK’s long term transition to low carbon heat.